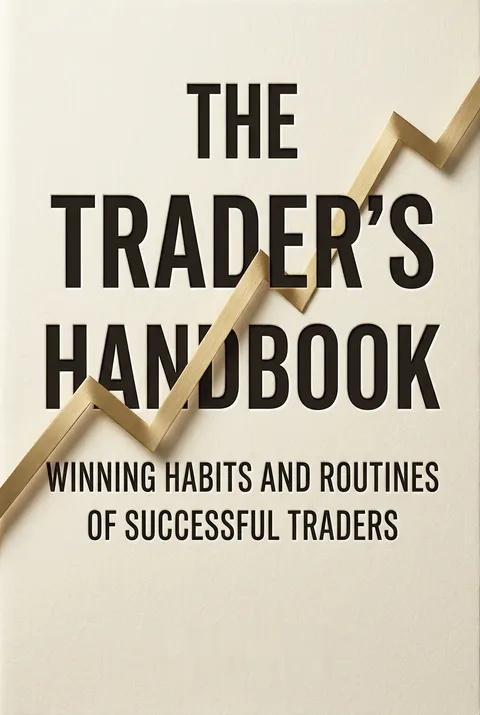


Key Takeaways
Sell the chart when a winner's character breaks, not its story
A good story can turn. In 1999, a portfolio manager held Charles Schwab as it surged on strong earnings and a promising shift to online brokerage. After a roughly 400% rise in 24 weeks, the stock began accelerating in a euphoric final push, a pattern the authors call a climax top. The trader recognized the change in the chart and sold, even as television celebrated the company. Schwab fell more than 65% within six months, then lost 87% during the 2000 to 2003 bear market.
Price tests the narrative. The lesson is not that fundamentals do not matter. They can help explain why a stock rises, but price and volume show whether buyers still support it. A celebrated company is not a reason to ignore a weakening trend.
The Schwab episode captures a persistent investing trap: people become attached to the explanation for a stock's rise and treat contrary price evidence as temporary noise. Behavioral finance describes this as a form of confirmation bias, where investors seek evidence that supports an existing belief. The chart offers a useful counterweight because it records actual transactions rather than intentions or forecasts. It is not an oracle, however. A sharp move can reverse and then recover, so selling rules need to fit a trader's time horizon and tolerance for false signals. The practical gain is not perfect timing, but a disciplined way to challenge a persuasive story.
Trade favorable risk, not a fantasy of near-certain wins
An edge is a long-run advantage. In the book, an edge is a repeatable feature of a process that can produce a positive expectation over many trades. It does not promise that the next trade will work. A setup is a broader chart pattern that creates an attractive potential reward relative to the risk; an entry tactic is the shorter-term trigger used to enter it.
Define failure first. A useful trade has a clear price that would show the idea is failing, and that level must be both close enough to limit the loss and meaningful enough to avoid being triggered by ordinary fluctuations. This changes the question from “Will this stock rise?” to “What is the loss if this idea is wrong, and is the possible gain worth it?”
This framework resembles decision-making under uncertainty in fields such as medicine: a good decision is judged by the quality of the process and the odds available at the time, not by one outcome. A losing trade can be well executed, just as a winning trade can be reckless. That distinction helps prevent traders from learning the wrong lesson from short streaks. The caveat is that a favorable chart pattern does not establish a durable statistical edge by itself. Costs, slippage, market conditions, and a sufficiently large sample all matter when testing whether a pattern has earned confidence.
Master one trading style before collecting more strategies
Progress has recognizable stages. The authors describe a path from random, losing trades, through volatile boom-and-bust results, toward consistent profitability and then stronger performance. A trader can use an equity curve, a chart of account value over time, to see which pattern fits. A steadily rising curve with shallower setbacks suggests a different process from gains repeatedly erased when market conditions change.
Reduce competing noise. The book recommends choosing one trading time frame, narrowing attention to a few stocks and setups, and writing clear rules for entries, risk, and exits. The aim is not to stop learning. It is to practice one approach long enough to understand its strengths and failure conditions before adding another. The authors note that many traders need experience across roughly two bull-to-bear cycles to develop consistency.
The staged model works as a diagnostic, not a ranking of personal worth. It directs attention toward the current bottleneck: random decisions, inconsistent execution, or refinement of a strategy that already works. That focus resembles deliberate practice, where improvement comes from repeating a bounded skill with feedback rather than accumulating information indiscriminately. The two-cycle estimate is a useful reminder that skill develops slowly, but it should not become a promised timetable. Traders differ in capital, time, temperament, and market exposure. A stage label is valuable only if it leads to a concrete adjustment in behavior.
Read volume, tightness, and relative strength as clues to demand
Price and volume tell a joint story. A daily bar shows where price opened, traded, and closed; its closing position within the day's range can indicate whether buyers or sellers prevailed. Volume adds context: unusually high activity during a breakout can signal strong demand, while quiet trading during a contraction can suggest that selling pressure is drying up. The authors look for leaders that trend cleanly, hold important moving averages, and outperform the market during pullbacks.
Context matters more than a single signal. They cite an estimate that institutions account for about 90% of trading volume, and argue that institutional accumulation can help create sustained trends. But volume does not identify who bought or why. A tight chart or a strong close is a clue to investigate, not proof of future gains.
The strength of this approach is its emphasis on observable behavior over elaborate indicator collections. It also treats signals as contextual: a strong close matters more when it appears in a constructive pattern than when isolated from the broader trend. That is a useful antidote to pattern-matching by label alone. Yet interpreting volume as institutional buying is necessarily inferential. A transaction has both a buyer and a seller, and public volume data cannot reveal their identities or intentions. The framework is best understood as a way to organize evidence about supply and demand, not as a direct view into institutional portfolios.
Screen for a real growth theme, then wait for the chart to agree
Selectivity starts before the buy. The authors' TIGERS checklist combines a compelling market theme and differentiated innovation with rapid growth, chart evidence of demand, relative strength, and an actionable setup. Their examples favor earnings or sales growth of at least 25% year over year, with faster or accelerating growth preferred. They also look for companies in strong industry groups and stocks outperforming the market.
A good company is not enough. A screen narrows thousands of stocks to a manageable list, but traders still inspect charts and wait for a pattern they know how to trade. The book identifies three recurring opportunity periods in a stock's life: early trading after an IPO, a later transition as institutional interest builds, and renewed momentum after a long base or correction. These are areas to investigate, not automatic buy signals.
The checklist combines two different kinds of evidence: a business may have a credible growth engine, while its price action may show whether investors are acting on that potential. Requiring both can reduce the temptation to buy a persuasive story before demand appears. Screening also has a quieter benefit: changes in the number of qualifying stocks can reveal whether market leadership is broadening or thinning. One important limitation is that thresholds such as quarterly growth above 25% are filters, not universal laws. They can exclude early-stage companies or favor firms with unusual comparison periods, so a screen should serve the strategy rather than define reality.
Plan the entry, pivot, and exit before the stock starts moving
Setups need execution rules. The book highlights three larger patterns: a Launch Pad, where several moving averages converge during a consolidation; a gapper, where a stock jumps on heavy volume and a catalyst; and a base breakout, where price rises through resistance after weeks of consolidation. Each offers a different context, but none removes uncertainty.
Use a precise trigger. Entry tactics include buying a reclaim of a key support level, a short consolidation breakout, or a pullback to a moving average the stock has previously respected. For a gap, traders might use the opening range or a continuation through the gap day's closing price. In each case, the plan names a pivot that triggers entry and a nearby technical level that invalidates it. A short focus list and advance alerts help prevent chasing.
Separating the larger setup from the immediate entry is a powerful way to prevent a familiar error: confusing a promising stock with a timely trade. It resembles staged decision systems in engineering, where a project must pass several distinct checks before resources are committed. The book's examples also make room for re-entry after a stop-out if the broader pattern remains intact. That flexibility is important, but it can become an excuse to keep trying without new evidence. A trader needs rules for distinguishing a temporary shakeout from a setup that has genuinely deteriorated.
Calculate account-level risk before deciding how large to trade
Risk is more than position size. The authors define total open risk as the sum of each position's dollar value multiplied by its distance to the planned stop. The result estimates the portfolio loss if every stop is reached. For example, a 3% loss on a position equal to 20% of the account costs 0.6% of the account, before slippage or gaps.
Stops and sizing work together. A stop should sit beyond a meaningful chart level, but close enough that a failed trade produces a manageable loss. The authors suggest that many growth-stock trades use stops around 1% to 4%, with wider room for more volatile names. They caution newer traders against copying experienced traders' large positions. Start with manageable size, and increase only after demonstrating consistent execution.
This account-level calculation turns a vague warning about risk into a quantity that can be compared with a trader's tolerance. It also exposes why a portfolio of several stocks may not be safe merely because it is diversified: their stops can be far away, or their prices may fall together during a market shock. The estimate is still conditional. Stops do not guarantee an exit at the stated price, especially after overnight news or a sudden liquidity gap. A robust plan therefore treats calculated open risk as a useful baseline, not a maximum loss guaranteed by arithmetic.
Let market conditions turn your exposure up or down
A market cycle guides aggressiveness. The book distinguishes longer shifts in market liquidity from shorter swings driven by fear, greed, accumulation, and profit-taking. Traders can define a cycle using index trends, breadth, and leading stocks. One example for swing traders begins an upcycle when the Nasdaq 100 ETF closes above its rising 21-day exponential moving average. It ends after two closes below that average, with the second close below the prior day's low.
Treat signals as prompts. A cycle turning positive is a reason to test the waters, not to invest all at once. If early trades work and leaders strengthen, exposure can increase. If trades fail or conditions weaken, traders can reduce positions, tighten stops, or step aside. For newer traders, the authors recommend especially clear sell rules, such as taking partial profits and trailing the remainder using a relevant moving average.
The market-cycle framework recognizes that a strategy's performance depends partly on its environment. This is analogous to adaptive control systems, which change their response when feedback indicates that conditions have shifted. Its most important discipline may be gradual adjustment: a signal invites testing, while successful trades provide further evidence. But moving averages necessarily react after price has moved, and sensitive rules can produce false starts. The right test is not whether a cycle indicator predicts every turn. It is whether it improves the trader's decisions and drawdowns over a meaningful sample, compared with a simpler alternative.
Turn trade reviews into evidence, not excuses or hindsight
Review decisions, not just returns. The authors recommend studying the best five trades and the worst ten from a period, then comparing the chart, setup, entry, position size, market conditions, and execution against the original plan. A short daily journal can record the reasoning and emotions that later become hard to recall accurately. Useful metrics include average gain and loss, risk-to-reward, trade duration, and the largest loss, not win rate alone.
Build a reference library. A model book collects leading stocks from a chosen year, cycle, or setup, with annotated charts and relevant business information. Trading studies can test focused questions about patterns across different conditions. The point is to find repeatable features, including failures, and revise written rules when a sufficient body of evidence supports a change.
Post-trade analysis is most valuable when it separates process quality from outcome and converts a recurring error into a specific rule or routine change. Written records help counter hindsight bias, the tendency to remember past decisions as more obvious than they were. Model books can also train visual recognition by exposing traders to many examples rather than one memorable winner. Their danger is selection bias: a collection of exceptional stocks can make patterns look more reliable than they are. Including failed setups, ordinary outcomes, and different market environments makes the exercise more scientifically useful.
Analysis
The book's central contribution is not a secret stock pattern. It is a way to connect observation, decision, risk, and review into one operating system. Its narrative begins with a trader who could have been seduced by a celebrated company's prospects, but instead treated the chart as evidence capable of overruling the story. The Schwab trade then becomes a compact model of the larger argument: skill means having a process that can survive both emotional success and changing conditions.
The system has four linked layers. First, selection narrows attention to companies with growth, leadership, and evidence of demand. Second, setups and entry tactics turn that attention into specific decisions. Third, stops and position sizing determine how much a wrong call can cost. Fourth, journals, statistics, and model books create a feedback loop. None is sufficient alone. Strong stock picking without exits can give back gains; tight stops without sound entries can generate repeated losses; and detailed records without disciplined interpretation can simply produce more elaborate rationalizations.
The book's most useful distinction is between risk per position and risk across the account. That distinction forces a trader to think in portfolio terms rather than treating each trade as an isolated bet. Its staged development model also makes improvement concrete: reduce random choices, specialize, stabilize execution, then refine performance. This is more credible than implying that expertise arrives through finding one perfect setup.
The framework remains a particular style of growth and momentum trading, not a universal market law. Moving averages, volume surges, growth thresholds, and market-cycle rules are heuristics that require testing against actual costs and the trader's own horizon. Historical winners are especially vulnerable to hindsight and survivorship bias. The authors' strongest safeguard is therefore also their most important prescription: keep written rules, study failures as well as winners, and let evidence revise the playbook. The practical promise is not certainty, but better-controlled uncertainty and fewer catastrophic mistakes.
People Also Read




Glossary
TIGERS
Stock-selection checklistThe authors' checklist for identifying potential growth leaders. It combines a strong market theme and differentiated innovation with company growth, chart evidence of demand, relative strength, and a tradeable setup. TIGERS is a screening aid, not a prediction formula: candidates still require chart review, a suitable market environment, and a defined risk plan.
Equity Curve
Account value over timeA time-series chart of a trader's account value or performance. The book uses it to diagnose development: a volatile decline suggests unstructured losses, while repeated gains followed by deep reversals suggest boom-and-bust behavior. A steadily rising curve with shallower drawdowns can indicate improving consistency, though market conditions also affect its shape.
Edge
Long-run trading advantageA repeatable characteristic or process that gives a trader a favorable expectation across many trades. An edge does not make a particular trade certain to succeed, and it can weaken as market conditions change. The book treats risk management as essential because even a valid edge can produce losing streaks.
Setup
Larger trade patternA recurring chart formation that combines relevant market or stock characteristics with a potential opportunity to enter at favorable risk relative to possible reward. Examples in the book include consolidations, gap-driven moves, and converging moving averages. A setup provides context, but an entry trigger and an invalidation level are still needed.
High Volume (HV) edges
Unusual volume signalsThe book's labels for unusually large trading-volume events that may accompany a change in a stock's character. HVE refers to highest volume ever, HVIPO to highest volume since the IPO week, and HV1 to highest volume in a year. These signals are considered more significant when paired with a catalyst and constructive price action.
Launch Pad
Moving-average consolidation setupA setup in which several key moving averages converge while a stock consolidates. The authors look for it near the start of a potential uptrend, particularly when a group of related stocks is also strengthening. Once the pattern develops, a trader still needs to identify a specific pivot and a logical level for managing risk.
N-factor
Catalyst for renewed growthA meaningful change in a company or its industry that can alter expectations for future growth. Examples include a new product, a major technology shift, regulatory change, or an earnings surprise. The book emphasizes that a compelling catalyst matters most when it is supported by actual business growth and visible demand in the stock.
Progressive exposure
Risk adjusted to feedbackThe practice of increasing or reducing trading size in response to market conditions and recent results. Traders test the waters when conditions improve, add exposure as positions and market leaders show strength, and scale back when trades fail or the environment deteriorates. It treats risk as adjustable rather than fixed.
Relative Strength line
Stock versus market performanceA chart line formed by comparing a stock's price with a market index, typically an index ETF. An upward trend indicates that the stock is outperforming the index; the line's absolute value is not meaningful. Traders use it to notice stocks holding up or advancing while the broader market weakens.
Total open risk
Portfolio loss at planned stopsAn estimate of how much a portfolio could lose if all current positions reached their planned stop levels. For each position, the trader multiplies its dollar size by the percentage distance to its stop, then adds the results. The calculation helps compare total risk with market conditions and personal risk limits, but cannot guarantee the actual exit price.
Model book
Annotated examples of winnersA curated collection of leading stocks from a selected period, market cycle, or setup. A model book typically combines annotated charts with relevant company, industry, earnings, sales, and catalyst information. It provides historical examples for study and helps traders build familiarity with recurring patterns, while requiring failed examples to avoid learning only from survivors.
Download PDF
Download EPUB
.epub digital book format is ideal for reading ebooks on phones, tablets, and e-readers.








