

Key Takeaways
Treat a second paycheck as risk exposure unless you keep it flexible
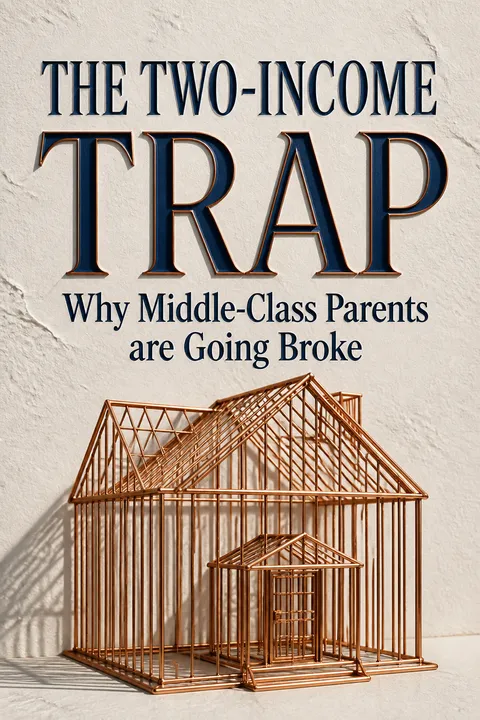
More income, less margin. The Two-Income Trap describes how families can earn more yet become more vulnerable when both paychecks are needed to maintain a costly standard of living. A second income might once have served as backup during a layoff or illness. But when families commit it to a larger mortgage, child care, insurance, and other recurring bills, it no longer acts as a reserve. The household can be left with less room to absorb a shock than a family that planned its expenses around one income.
The authors compare a typical family from 1973, with one earner, to a two-earner family in 2000. The newer household earned about 75 percent more, yet had roughly $800 less each year after major fixed costs. That comparison is an illustration, not a budget that fits every family. Its warning is broader: income is not security if it is already spoken for.
What's striking is the distinction between earning capacity and resilience. A household can look prosperous on an annual income statement while remaining fragile month to month, much like a business with high sales and no operating reserve. This shifts planning from asking how much a family earns to asking what happens when one stream stops. The argument does not make two incomes inherently unsafe: a second earner can provide genuine protection when the family avoids building every recurring expense around both paychecks. The key variable is whether added income creates options or merely raises the cost of keeping life unchanged.
Families bought middle-class necessities, not a national epidemic of luxuries
The spending story changes. The authors challenge the claim that widespread financial distress mainly comes from families buying too many fashionable extras. Comparing inflation-adjusted spending for families of four in the early 1970s and around 2000, they find that families spent 21 percent less on clothing, 22 percent less on food, and 44 percent less on major appliances. Spending on electronics and computers did rise, but those increases were modest beside the cost of housing, child care, insurance, and education.
The crucial distinction is between optional purchases and commitments that are hard to unwind. A family can stop buying restaurant meals more easily than it can sell a house, change a school, or end a long-term loan. The book argues that many parents used a second paycheck not for extravagance, but to compete for what they believed their children needed: a safe home, good schools, reliable transport, and education.
This reframing matters because visible consumption is easy to blame, while fixed costs are less obvious and more politically difficult to discuss. It also helps explain why a modest cut to discretionary spending may barely change a household's exposure to risk. Still, national averages cannot prove that no individual family overspent, and the book does not claim otherwise. The stronger point is comparative: a few more electronics purchases cannot plausibly explain the full rise in financial collapse if several large essentials became more expensive or more difficult to access.
When school quality follows the address, parents bid up housing
A school can raise a mortgage. The book argues that school assignment by neighborhood turns home-buying into a competition for educational access. Parents who believe good schools and safe streets are concentrated in a small set of communities bid against one another for homes there. The authors cite research finding that school performance can affect nearby home values, and describe a Philadelphia neighborhood where a new elementary school was followed by a sharp increase in housing prices.
That pressure does not end at the property line. Preschool became a costly expected step for many families, while college tuition rose as parents treated a degree as essential to a child's prospects. The authors propose loosening the link between a family's address and its public school, alongside broader access to preschool. Their particular voucher proposals are policy arguments, not settled conclusions, but their diagnosis is clear: when opportunity is rationed by location, parents may pay a premium for access.
The useful insight is that families often compete for access to public goods through private purchases. A house then functions as more than shelter: it becomes an admission ticket to a school district. That pattern can make each family's choice individually sensible while driving collective costs upward. The proposed school-choice remedies deserve scrutiny, since changing assignment rules cannot by itself equalize school quality, transportation, or neighborhood safety. Yet the underlying question remains powerful: why should a child's educational prospects depend so heavily on the purchasing power of the adults who choose an address?
Count caregiving and backup earning as real household assets
Unpaid work has economic value. The authors describe a stay-at-home parent as an all-purpose safety net: someone who can seek paid work after a partner loses a job, care for a sick child, or help an aging relative without sacrificing another paycheck. The value may be invisible in ordinary months, but it can become decisive during a crisis. One example is Elizabeth Warren's mother, who entered the workforce after her husband suffered a heart attack and could no longer earn his former salary.
The contrast is not simply between a working parent and a parent at home. The authors' point is that families give up flexibility when they rely on both incomes and have no savings, paid leave, or reliable care available. A two-earner household can still build protection through savings, insurance, and supportive services. The relevant question is what replaces the backup capacity that unpaid care once provided.
This section makes an important accounting correction: unpaid care is productive work, even when it does not appear as wages. It also connects household finances to labor-market design. Paid leave, disability coverage, and dependable care can preserve a family's ability to respond to emergencies without requiring one parent to remain outside paid employment. The analysis is strongest when it treats flexibility as the asset, rather than treating the traditional division of labor as the ideal. Otherwise, a critique of economic risk can inadvertently romanticize unpaid work and obscure the choices many women gained by entering the workforce.
Two earners can double exposure while fixed costs erase the cushion
More workers, more possible shocks. A two-earner family has two people who can lose jobs or become unable to work. The authors estimate that about one in sixteen dual-income families could experience a job loss in a given year, compared with a lower risk for a one-earner household in their historical comparison. They also report that involuntary job loss became more common between the 1970s and early 1990s. These risks matter more when mortgages, child care, car payments, and insurance leave little room to reduce spending quickly.
The book also tracks medical problems and family breakups. Nearly nine in ten families with children in its bankruptcy study reported a job problem, medical problem, or family breakup as a reason for filing, and many reported more than one. A job loss can trigger insurance problems; illness can reduce earnings and increase care needs. The danger is not one isolated event, but several pressures arriving before a household recovers.
This is a useful application of portfolio thinking to family life. Two income sources diversify risk only if they are not exposed to the same shock and if the household can adjust when one disappears. If both adults work in the same vulnerable industry, for example, their incomes may not be independent; if every dollar is committed, even independent incomes offer little flexibility. The book's simple doubling logic is a warning rather than a complete risk model. The broader lesson is to examine correlation, insurance, and the time required to reduce expenses, not merely count paychecks.
A divorce often begins with debts the marriage already could not carry
The financial damage starts earlier. The authors argue that many newly single mothers are not beginning from a stable household and then losing half its income. During marriage, both paychecks may already have been committed to housing, child care, and other fixed costs, with little savings left. When a spouse leaves, the remaining parent faces the same bills on less income, plus legal fees, new household expenses, and the difficulty of changing a child's home or school.
Gayle Pritchard, a working mother with three children, kept the family home after her husband moved out. Her income could cover daily needs, but not the mortgage as well. The book also shows that a divorce decree does not erase joint debts: creditors can pursue either signer. Its analysis resists making child support the sole solution. Many fathers pay what they owe, and some have little capacity to pay more; financial strain can affect both households.
The central analytical move is to treat divorce as a stress test of the balance sheet built during marriage, not as the moment the financial problem first appears. That helps explain why policies focused only on enforcement after separation may have limited effect. It also prevents a simplistic story in which one parent is always the solvent party and the other the sole victim. The authors' examples do not diminish the gendered burden of caregiving or the persistent income gap. They show that fairer support rules cannot create resources that a strained household never had.
Easy credit turns a temporary shock into a lasting financial trap
Debt fills the missing cushion. The authors trace the growth of consumer lending to legal changes beginning in the late 1970s that allowed lenders to apply interest rates from states with looser limits across state borders. They argue that credit shifted from a cautious loan granted after close review to a widely marketed product. In their account, families often used debt to manage job loss, medical bills, or a breakup, rather than to finance a spree of luxury purchases.
The book describes credit card balances rising from under $10 billion in 1968 to more than $600 billion by 2000, in inflation-adjusted terms. It also documents expensive subprime mortgages, late fees, and loans that could put a home at risk. The authors propose restoring limits on interest rates and curbing harmful lending. Their deeper warning is that a loan can bridge a shortfall, but high costs and collateral can turn a temporary setback into a long-term loss.
The account highlights an important institutional feature of borrowing: the same product can provide liquidity in an emergency and intensify the emergency through fees, interest, and collateral. That dual role argues for scrutiny of both access and terms, rather than treating more credit as automatically empowering or automatically harmful. The book's case for interest-rate limits is a specific policy remedy whose effects depend on design and lender response. Its broader contribution is to ask who bears the downside when credit is marketed to households with little room for error.
Bankruptcy is often a last resort, not evidence of bad character
Failure is not a moral diagnosis. The authors challenge the idea that rising bankruptcy filings prove that debtors have become careless or dishonest. In their interviews, more than 80 percent of families said they would be embarrassed if others learned they had filed. Many had spent over a year struggling before seeking legal protection. Among families with children, nearly nine in ten cited job loss, medical problems, or family breakup as factors in their financial collapse.
Ruth Ann and James Wilson illustrate the human cost. After James lost his job, the couple sold belongings, borrowed from relatives, and fell behind on their mortgage. Their seven-year-old son eventually answered a collection call, prompting Ruth Ann to seek bankruptcy protection. The book does not claim that no one overspends or commits fraud. It argues that those cases cannot explain the scale of distress, and that shame can keep families isolated when practical help is needed.
The distinction between choosing bankruptcy and feeling no shame about bankruptcy is essential. People can make a costly decision under constraint while still finding it humiliating. This challenges a common form of hindsight bias: observers see the filing but not the months of missed necessities and failed attempts to recover. The book's evidence comes from people who reached the bankruptcy system, so it cannot describe every indebted household. Even so, its account cautions against using a legal outcome as a shortcut for judging someone's character.
Run a financial fire drill before a pink slip or illness
Plan for interruption, not perfection. A Financial Fire Drill is the book's practical exercise for testing whether a household could withstand a crisis before one arrives. It asks families to examine income dependence, fixed costs, and emergency plans. The point is not to predict exactly what will go wrong, but to identify commitments that leave no room to respond.
The authors recommend asking three questions:
1. Could the household manage for six months if one income stopped?
2. Which recurring costs could be lowered before a crisis forces rushed decisions?
3. What insurance, savings, or family arrangements would help with illness, caregiving, or separation?
They caution against stretching to buy a home simply because a lender approves the mortgage, and against pledging home equity to pay unsecured debts during a crisis. They also advise paying first for the assets a family most needs to protect, rather than yielding to whichever creditor applies the most pressure.
The drill is effective because it turns an abstract risk into a household stress test. It resembles contingency planning in organizations: identify dependencies, preserve options, and decide in advance what matters most. The exercise is not a substitute for adequate wages, affordable care, or sound public policy, and some families have too little income to create meaningful reserves. Still, it can expose a dangerous mismatch between long-term commitments and unstable earnings. Its most practical insight is that a lender's approval measures willingness to lend, not a family's ability to absorb a shock.
Analysis
The book's most consequential move is to shift the explanation for middle-class financial distress from personal taste to household structure. Its account links three systems that are often examined separately: competition for child-centered opportunities, the conversion of two incomes into fixed commitments, and a credit market willing to lend when families have little slack. In this model, a second paycheck can raise housing prices and family expectations without producing a durable reserve. A job loss or illness then exposes the difference between income and security.
The narrative makes that argument legible through families such as Ruth Ann and James, whose collapse followed a layoff despite careful planning, and Gayle, whose marriage ended after the household had already committed both incomes to a home. These stories provide a human scale for the statistical argument. The Consumer Bankruptcy Project also gives the book unusually detailed evidence about people who filed. However, bankruptcy filers are a selected population, and the book's comparisons of representative family budgets are illustrative rather than proof that every family experienced the same causal pathway. The numerical claims describe the period studied, chiefly the 1970s through the early 2000s, and should not be mistaken for current estimates.
The thesis is also more precise than a simple case against dual-income families. The authors acknowledge that a second income can be useful if it remains flexible or is saved, and that a stay-at-home parent provides valuable capacity only when the household can manage on one paycheck. That insight translates into a general principle: resilience depends on the ability to adjust, not on a single ideal family arrangement. The policy proposals, including school choice, preschool access, savings incentives, disability coverage, and lending limits, are not equally persuasive or interchangeable. Their common purpose is to reduce the private cost of securing a middle-class childhood and prevent a short-term shock from becoming a permanent loss. The book is strongest as a diagnosis of fragile household economics, and more debatable as a blueprint for any one reform.
Review Summary
People Also Read

Glossary
Two-Income Trap
Income committed to essentialsA condition in which a family depends on two paychecks to cover recurring costs such as housing, child care, transportation, and insurance. Because both incomes are already committed, the second paycheck does not function as a reserve. If one earner loses work or the household faces illness or separation, fixed expenses can make the family more vulnerable than its higher combined income suggests.
All-Purpose Safety Net
Backup income and careThe authors' term for the economic flexibility provided by a parent who is available for unpaid caregiving and could enter paid work if the household faced a crisis. This parent may care for a sick child or older relative, or earn income after a partner's job loss. The concept emphasizes the financial value of available time and labor, not only wages.
Over-Consumption Myth
Blaming distress on luxuriesThe explanation that widespread household financial trouble results mainly from families buying unnecessary goods and failing to control spending. Warren and Tyagi test this claim against inflation-adjusted expenditure data. They argue that spending on several common consumer categories had fallen or risen only modestly, while major fixed costs tied to housing, child care, health care, and education absorbed more family income.
Myth of the Immoral Debtor
Bankruptcy as moral failureThe belief that rising bankruptcy filings show that debtors have become less responsible, feel little shame, or exploit the system despite being able to repay. The authors counter with interviews and financial data indicating that many families delay filing, feel acute embarrassment, and face job loss, medical problems, or family breakup. The term challenges moral judgments that obscure economic causes.
Financial Fire Drill
Household crisis stress testA planning exercise that asks a family to prepare for a financial emergency before one occurs. It examines whether the household could manage after losing an income, which fixed costs could be reduced, and what savings, insurance, or care arrangements are available. The exercise favors advance decisions and flexible commitments over relying on optimistic assumptions about how quickly a crisis will pass.
Added Worker Effect
Spouse enters work after income lossA term used in labor economics for the tendency of a spouse, often a wife in the studies discussed, to seek paid work when the other partner loses a job or suffers a lasting reduction in earnings. The book presents this response as one way a household with a previously nonworking adult could replace lost income, while noting that child care, skills, and weak local job markets can limit the effect.
Consumer Bankruptcy Project, 2001
Study of bankrupt householdsA research project that gathered questionnaires, court records, and telephone interviews from people filing consumer bankruptcy. Its core sample included cases from five states, with supplemental homeowner and rural samples. The research provides detailed evidence about bankrupt families' debts, circumstances, and reasons for filing, but it studies people who reached bankruptcy rather than a representative sample of all American households.
Download PDF
Download EPUB
.epub digital book format is ideal for reading ebooks on phones, tablets, and e-readers.








