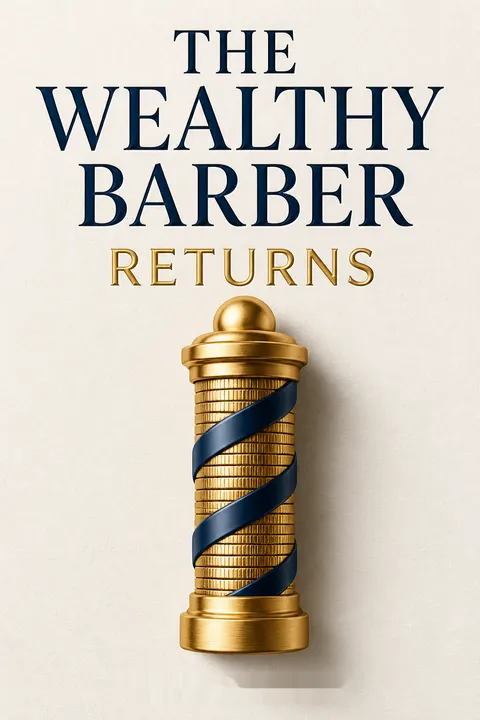


Key Takeaways
A modest spending cut can more than double what you save
The arithmetic is encouraging. Each after-tax dollar can be spent or saved. If you currently spend 96 cents and save 4 cents, trimming spending to 90 cents raises savings to 10 cents. That is a 6.25% cut in spending, but savings increase by 150%. The point is not that everyone can or should use those exact figures. It is that saving more may require a smaller lifestyle adjustment than it first appears.
Balance beats austerity. Chilton rejects the idea that today’s enjoyment and tomorrow’s security must be enemies. Saving funds future spending, including retirement, when wages stop. The practical task is to make room for both, rather than treating every dollar as a contest between present pleasure and future deprivation.
The reframing works because percentages are psychologically deceptive: a small reduction in a large spending base can produce a large increase in a small savings base. That helps replace the intimidating question, “How can I save so much more?” with the more manageable question, “Where could a little spending go?” The argument is strongest when the cut comes from low-value consumption, not necessities. For households already struggling to cover housing, food, or care, arithmetic alone cannot create a surplus. The book’s balance principle is useful, but its feasibility depends on income as well as discipline.
Automate saving before your wants get a vote
Make saving the first bill. Chilton’s central habit is to transfer money into savings automatically through payroll deductions or scheduled bank transfers. The reason is practical: when people spend first and plan to save what remains, current desires tend to claim the remainder. A budget may identify the problem, but it cannot guarantee follow-through. An automatic contribution puts the future goal ahead of the next discretionary purchase.
Start now, not someday. Chilton describes forced saving as more dependable than waiting for a perfect plan or a calmer month. Many people who begin with automatic contributions report less disruption to their lifestyles than they expected. The point is not that saving never pinches. It is that a system can make a difficult choice consistently, without requiring a fresh act of willpower every payday.
Automation is a commitment device: a choice made in advance limits the influence of a later, more impulsive self. That is especially apt for a book arguing that ordinary people face a constant sales pitch to spend. The method also turns an abstract aim into a repeatable behavior, which is often more useful than tracking progress toward a vague goal. Still, automatic saving should not become blind saving. Contributions need to fit essential expenses and high-interest obligations, and transfers should be reviewed when income or family needs change.
Make impulse spending inconvenient, because willpower loses at checkout
Reduce access to temptation. Chilton uses a simplified brain model: a deliberate “executive” plans for the future, while an emotionally responsive “lizard” favors immediate rewards. The model is not a full account of neuroscience, but it captures why a desirable purchase can overpower good intentions. His answer is not to rely on heroic self-control. It is to create a pause between temptation and payment.
Add useful friction. One woman kept her cards frozen in ice so buying on impulse required a long delay. Less dramatic options include leaving cards at home, carrying limited cash, or keeping one low-limit card for routine use and another secured for genuine needs. These tactics make spending less immediate and give an impulse time to cool.
The insight connects personal finance to choice architecture: the design of a decision environment can change behavior without changing anyone’s goals. A delay is particularly valuable because it interrupts the link between emotional arousal and purchase. This approach is more realistic than demanding perfect restraint in settings deliberately built to encourage buying. However, friction should be selective. Making every transaction difficult can create problems in emergencies or for people with limited mobility or access to banking. The goal is to obstruct predictable impulse purchases, not essential spending.
Widen your comparison group until gratitude crowds out envy
Notice who sets the standard. People often judge their lifestyle against friends, colleagues, and people they follow, not against their own needs or means. Chilton calls these comparison circles reference groups. When they include much wealthier people, expensive homes, trips, and possessions can start to feel ordinary, even necessary. Easy credit makes it possible to imitate that appearance without having the wealth behind it.
Restore perspective. Chilton recommends looking beyond affluent peers to people facing severe hardship and to earlier generations whose daily conveniences were far fewer. His examples range from safe water and electricity to modern groceries, phones, cars, and television. The point is not that prosperity eliminates real problems. It is that constant attention to what others own can make substantial advantages invisible.
The useful move is not to rank suffering, but to question the narrow sample used to define “normal.” Social comparison can turn a neighbor’s unusual purchase into a personal benchmark, while broader context can reveal that the benchmark was arbitrary. Gratitude can help interrupt that escalation and protect spending from status competition. Yet global hardship should not be used to dismiss local insecurity or public problems. Perspective is most constructive when it expands appreciation without implying that people should accept avoidable hardship.
Treat every upgrade as the start of a spending chain
One purchase can recruit another. The Diderot effect describes how acquiring something new can make existing possessions feel mismatched, prompting a series of related purchases. Chilton recounts Denis Diderot’s 18th-century account of a new dressing gown that made his furniture and surroundings seem shabby. The gown was only the beginning. A modern equivalent might be buying a dress, then deciding it needs matching shoes and a purse.
Budget for the chain. Home renovations are especially prone to this pattern: an updated bathroom makes an older kitchen seem unacceptable, and one project expands into several. Before buying or renovating, consider the likely follow-on costs, not just the first price. Chilton is not arguing against enjoyment or improvement. He is warning that the initial purchase can quietly reset expectations for everything around it.
This is a powerful account of how preferences can shift after a purchase. People do not merely want an object; they also want it to fit the identity and environment they now imagine for themselves. That explains why isolated price comparisons can miss the true cost of an upgrade. A useful safeguard is to define the full project before starting and decide what will remain unchanged. The idea needs nuance, though: related purchases can be genuinely useful, and some renovations improve safety or accessibility. The warning is against unplanned escalation, not every sequence of improvements.
Buy a home only after retirement saving fits comfortably
Approved is not affordable. A lender may judge a mortgage by income and monthly debt payments. Chilton argues that borrowers must also account for taxes, utilities, upkeep, retirement contributions, and other goals. He calls debt “good” only when it buys an appreciating asset, leaves appropriate saving intact, and is repaid before retirement. A valuable home does not make an unaffordable payment harmless.
Treat credit as someone else’s money. Lines of credit can have low rates and small interest-only payments, but the principal still has to be repaid. One borrower treated a $60,000 renovation as a $150 monthly expense because that was the interest at 3%; the $60,000 itself had not disappeared. Chilton also warns that lenders may offer more credit than a borrower’s broader plan can safely support.
The distinction between a lender’s approval and a household’s capacity is essential. Credit underwriting typically answers whether payments appear manageable under specified assumptions; it does not decide whether those payments leave room for a secure retirement or a tolerable life. Chilton’s warning is particularly relevant when a low interest rate makes a large balance feel small. At the same time, homeownership is not automatically a mistake, and housing markets differ widely. The durable lesson is to judge the full cash-flow commitment, not to treat a bank’s limit as a recommended target.
Track spending to discover which purchases earn their place
Make the invisible visible. Chilton changed his mind about recording expenses after seeing how often people underestimated cars, restaurant meals, and purchases under $20. A spending summary can reveal habits before any formal cutback begins. It can also help distinguish spending that brings lasting satisfaction from money that slips away with little reward.
Count value in more than dollars. Chilton suggests treating money as time: after-tax earnings represent hours of work, so a purchase can be evaluated by the time it costs. He also encourages spending more on experiences and less on possessions when that better matches a person’s priorities. Shared events can create memories and anticipation, while objects may lose their novelty. The aim is not to be cheap, but to spend deliberately on what feels worthwhile.
Expense tracking is useful not only as bookkeeping, but as feedback. It tests remembered behavior against actual behavior, much as a food or time diary can expose patterns people do not notice in daily life. The book’s “joy” lens adds a valuable question to conventional cost control: what does this spending do for the person making it? Experiences often have social and narrative value, but no universal ranking fits everyone. A hobby purchase can matter deeply, while travel may not. The measure should be personal usefulness, not a new rule about what counts as a good life.
Start saving early, because delay makes the required contribution soar
Time changes the math. Chilton compares twin brothers who each invest $4,000 annually at an assumed 8% return. Hank saves from age 25 for ten years, then stops; Simon waits until 35, then saves for 30 years. At 65, Hank has about $629,741, while Simon has about $489,383, despite Simon contributing three times as much. If Hank had continued saving, his balance would be about $1.12 million. The example is hypothetical, but it shows how a later start sacrifices years of compounding.
Use targets as guides. Chilton reports a common recommendation of saving 10% to 15% of gross income, while noting that pensions, income, and retirement needs change the calculation. Do not count an uncertain inheritance as a substitute for saving.
The example makes opportunity cost vivid: the loss is not only the money missed during the delay, but also the future growth that money could have generated. It also challenges the comforting idea that a person can easily compensate by saving more in middle age. Still, the 8% return is an assumption, not a promise, and the exact outcome changes with inflation, fees, taxes, and investment mix. The recommendation to start early is robust; the illustrative dollar totals should be treated as a teaching device, not a forecast.
Choose low-cost market exposure over an expensive hunt for winners
The average cannot be beaten by everyone. Before costs, investors collectively hold the market, so their combined return must equal the market’s return. Some investors can outperform, but others must underperform. Chilton’s point is mathematical, not a claim that every manager is equally skilled.
Fees tilt the odds. In his example, an index fund costs 0.5% annually while actively managed funds cost 2.3%. If the market returns 8%, the index investor keeps 7.5% before other considerations. The active group, as a whole, must start from the same market return and then pay higher costs. Picking future outperformers is difficult, and a strong past record has not proved a reliable selection method in Chilton’s experience. Understand what an index tracks and what you pay to own it.
The argument’s force comes from combining market arithmetic with a controllable variable: cost. Investors cannot know in advance which manager will outperform, but they can know a fund’s stated fees. Low-cost indexing therefore offers a strong default for people who do not have a demonstrable selection advantage. The conclusion is not that active management can never work. It is that an active manager must overcome both competitors and expenses, a high bar that should be tested against evidence rather than confidence or recent performance.
Expect stock-market returns to arrive in jolts, not a steady climb
Volatility is part of the deal. Chilton reports that since 1926 the S&P 500 rose more than 20% or fell in roughly two-thirds of years. A long-run average therefore does not describe a typical year. Investors who expect a smooth upward path may be more likely to panic when markets drop.
Make patience easier. Chilton favors choosing an appropriate stock allocation, rebalancing periodically, and avoiding constant monitoring. He tells of his father mistaking the number of fund units for their dollar value, then discovering that a holding had grown substantially. The story is funny because the father was uninvolved, but the principle is serious: frequent checking can provoke fearful decisions. Review a portfolio regularly enough to keep it suitable, not so often that every fluctuation becomes a command to act.
Realistic expectations function as emotional risk management. Someone who knows in advance that sharp declines are ordinary has a better chance of distinguishing a market setback from a broken plan. The father’s accidental indifference is memorable, but indifference should not mean neglect: an investor still needs an appropriate mix, periodic review, and attention to changing circumstances. The key distinction is between monitoring the plan and reacting to every price movement. One supports long-term discipline; the other can turn temporary volatility into permanent loss.
Compare debt paydown with investing using after-tax returns
Debt repayment can be an investment. Paying down an 18% credit-card balance avoids that interest, creating a powerful, predictable benefit that a risky portfolio is unlikely to match consistently. A low-rate loan may present a different choice. For a mortgage, the comparison depends on its rate, the likely investment return after costs and taxes, and the borrower’s comfort with risk.
Account rules matter. RRSP contributions may be especially attractive when the tax deduction is taken at a higher rate than withdrawals will face. TFSAs offer tax-free withdrawals, while RRSP withdrawals are taxable. The best choice depends on future tax rates and other rules. Chilton also warns against paying off a mortgage early and then stopping contributions: freed-up payments are not a substitute for continuing the original savings habit.
The strongest part of this framework is its insistence on comparing like with like. A guaranteed reduction in interest expense should not be casually compared with an investment return before taxes, fees, and risk. Tax shelters complicate the calculation, so a simple slogan about one account always winning is unreliable. The psychological side also matters: a mortgage payoff may reduce stress, while a volatile portfolio may be hard to hold through losses. A sound decision therefore combines arithmetic with the investor’s real capacity to stay the course.
Keep the plan simple, but make every cost and protection visible
Complexity is not sophistication. Chilton’s model is a farmer’s plain plan: automatic retirement contributions, a mix of guaranteed investments and stocks, debt repayment, help for a child’s education, an updated will, and insurance for a defined need. The point is not to copy the exact allocation, but to see how basic habits can cover the essentials.
Ask what advice costs. Chilton argues that clients should know their advisor’s compensation, the account’s performance, and the fees paid. He also favors taking an employer contribution match when available and generally prefers term life insurance for people who need temporary family protection, rather than bundling insurance and investments without comparing costs. Legal and insurance decisions depend on individual circumstances, so the book presents general principles rather than tailored advice.
A simple plan reduces the number of decisions that can be delayed, misunderstood, or sold as opportunities for unnecessary complexity. The farmer’s example is persuasive because it connects cash flow, investing, debt, family obligations, and estate preparation without pretending one portfolio suits everyone. Transparency is the necessary companion to simplicity: low complexity is not an excuse to ignore fees or protection gaps. Nor should simplicity become rigidity. A plan needs to adapt when health, dependents, income, or goals change, ideally with clear reasons for each adjustment.
Analysis
The book’s central argument is that personal finance is less a puzzle of prediction than a problem of behavior. Its advice repeatedly favors systems that survive ordinary human weakness: automatic saving, limited access to easy credit, visible spending, and investments that do not require forecasting. These recommendations fit together. Saving creates the surplus; restraint protects it; low costs and time allow it to grow. The memorable examples, from Diderot’s gown to a renovation charged to a line of credit, show how financial trouble often arrives by accumulation rather than through one spectacular mistake.
Chilton also makes a useful distinction between appearing wealthy and possessing resources that can support future choices. A large home, high credit limit, or expensive lifestyle can signal success while consuming the very cash flow that builds financial independence. His emphasis on experiences, gratitude, and spending according to personal priorities broadens the book beyond a narrow instruction to accumulate money. Wealth is framed as both financial capacity and freedom from the race to keep up.
The book’s greatest strength is its practical skepticism: lenders have incentives, investment forecasts are uncertain, and complex products can conceal costs. Its main limitation is that it sometimes makes saving appear more universally available than it is. Housing costs, unstable work, caregiving, and low incomes can prevent households from creating the surplus that the advice assumes. Behavioral tactics help people direct money, but cannot manufacture money they do not have. The retirement percentages, market examples, and Canadian account rules also reflect assumptions and conditions that should not be treated as timeless personal recommendations.
Taken as a whole, the book is best read as a defense of financial agency, not austerity. It asks readers to make fewer decisions under pressure, question the incentives around them, and protect time for compounding. Its recurring lesson is modest but demanding: a durable plan is not the cleverest one, but the one a person can actually live with.
Review Summary
The Wealthy Barber Returns receives mostly positive reviews, with readers appreciating its accessible approach to personal finance. Many find Chilton's humor and casual writing style engaging, though some feel it detracts from the content. The book is praised for its relevant Canadian financial advice, covering topics like RRSPs, TFSAs, and index funds. While some readers find the information basic, others value its straightforward guidance on saving, investing, and living within one's means. The book is particularly recommended for young Canadians or those new to personal finance.
People Also Read





Glossary
Diderot effect
Purchase-triggered spending chainThe tendency for a new possession to make existing possessions or surroundings seem inadequate, prompting additional purchases. The term refers to Denis Diderot’s account of acquiring an elegant dressing gown and then feeling driven to replace other furnishings to match it. The effect is especially relevant to upgrades, clothing, and home renovations.
reference groups
People used for comparisonThe people whose lifestyles shape a person’s sense of what is normal, desirable, or affordable. Friends, colleagues, and online acquaintances can act as reference groups. When those groups include people with much higher incomes, their spending can encourage someone to imitate a lifestyle that their own finances cannot support.
consumer surplus
Value above the priceThe difference between what a buyer believes a product is worth and the price actually paid. A buyer who would have paid $6 for a drink but pays $4 perceives a $2 surplus. Chilton notes that this judgment becomes less reliable for purchases whose pleasure changes over time.
declining marginal utility
Less pleasure from repetitionThe idea that repeated use of the same good often produces less additional satisfaction than the first use. Chilton applies the concept to purchases that feel exciting at first but become familiar, such as a new car or exercise equipment. Buyers may overestimate how long the initial excitement will last.
Prudently contained debt (PCD)
Capped borrowing with repaymentChilton’s label for a deliberately small line of credit used to finance one discretionary purchase at a time. The borrowers in his example agree not to borrow again until the balance is fully repaid. The capped amount limits exposure, while the desire to make another purchase motivates repayment.
The Rule of 72
Approximate investment doubling timeA shortcut for estimating how many years an investment takes to double when its return compounds annually: divide 72 by the annual rate of return. At 8%, the estimate is nine years. The approximation is most useful across moderate rates and becomes less accurate at extreme rates.
index
Summary measure of a marketA single statistical measure that summarizes a selected group of data, such as the share prices of companies in a stock market. An index is constructed by choosing its components and a weighting method. Investors cannot buy the number itself, but can buy funds designed to hold its components.
management expense ratio
Annual fund operating costThe annual percentage of a mutual fund’s assets used to pay management, administration, distribution, and other operating expenses. The expense reduces the return investors receive. In Chilton’s discussion, the distribution portion may also compensate an advisor, making it important to understand what services the fee pays for.
FAQ
What's "The Wealthy Barber Returns" about?
- Author's Perspective: "The Wealthy Barber Returns" by David Chilton offers a humorous and straightforward take on personal finance, focusing on saving, spending, and borrowing.
- Financial Advice: The book provides practical advice on managing money, emphasizing the importance of living within one's means and saving for the future.
- Unique Approach: Unlike traditional financial books, it avoids complex charts and math, instead opting for a conversational style that feels like a casual chat about money.
- Target Audience: It's aimed at Canadians but offers universal lessons applicable to anyone looking to improve their financial habits.
Why should I read "The Wealthy Barber Returns"?
- Humorous and Engaging: Chilton uses humor to make the often-dry subject of personal finance interesting and accessible.
- Practical Advice: The book provides actionable strategies for saving, spending, and borrowing that can be applied immediately.
- Common Sense Approach: It emphasizes simplicity and common sense in financial planning, making it suitable for readers of all financial literacy levels.
- Relatable Content: The conversational tone and real-life examples make the advice relatable and easy to understand.
What are the key takeaways of "The Wealthy Barber Returns"?
- Live Within Your Means: The book stresses the importance of spending less than you earn as the foundation of financial security.
- Pay Yourself First: Chilton advocates for automatic savings to ensure you prioritize your financial future.
- Avoid Excessive Debt: The dangers of credit cards and lines of credit are highlighted, urging readers to be cautious with borrowing.
- Focus on Simplicity: Financial planning doesn't have to be complicated; simple, time-tested strategies often work best.
What are the best quotes from "The Wealthy Barber Returns" and what do they mean?
- "Pay yourself first": This emphasizes the importance of saving a portion of your income before spending on anything else.
- "Live within your means": A reminder that financial stability comes from spending less than you earn.
- "Simplicity is the ultimate sophistication": Encourages readers to avoid complex financial products and stick to straightforward strategies.
- "Happiness flows from relationships, health, and making a difference, not from a $1,000 solid-brass kitchen faucet": Highlights the idea that true wealth is not about material possessions but about life satisfaction.
How does David Chilton suggest managing debt in "The Wealthy Barber Returns"?
- Avoid Credit Card Debt: Chilton warns against the convenience of credit cards, which can lead to overspending and high-interest debt.
- Be Cautious with LOCs: Lines of credit are likened to giant credit cards; they should be used responsibly and not treated as extra income.
- Prioritize Debt Repayment: Focus on paying down high-interest debts first to reduce financial stress and improve cash flow.
- Consider the Cost of Borrowing: Always be aware of the interest rates and terms associated with any debt to avoid long-term financial strain.
What is the "Pay Yourself First" strategy in "The Wealthy Barber Returns"?
- Automatic Savings: Set up automatic transfers to savings accounts to ensure you save before spending.
- Prioritize Savings: Treat savings as a non-negotiable expense, just like rent or utilities.
- Build a Habit: Consistent saving, even in small amounts, can lead to significant financial growth over time.
- Financial Security: This strategy helps build a financial cushion, reducing reliance on credit and increasing peace of mind.
How does "The Wealthy Barber Returns" address the concept of living within your means?
- Spending vs. Saving: The book emphasizes the need to balance current spending with future savings to achieve financial goals.
- Avoid Lifestyle Inflation: Resist the urge to increase spending as income rises; instead, focus on increasing savings.
- Budgeting Basics: While not heavily focused on budgeting, the book encourages awareness of spending habits and making conscious financial choices.
- Long-term Benefits: Living within your means reduces financial stress and allows for a more secure and enjoyable retirement.
What does David Chilton say about investing in "The Wealthy Barber Returns"?
- Index Funds: Chilton suggests considering index funds for their low costs and market-matching returns.
- Avoid Market Timing: He advises against trying to predict market movements, emphasizing a long-term investment approach.
- Diversification: Spread investments across different asset classes to reduce risk and increase potential returns.
- Focus on Costs: Be mindful of investment fees, as they can significantly impact long-term returns.
How does "The Wealthy Barber Returns" suggest handling unexpected expenses?
- Emergency Fund: While Chilton is skeptical about traditional emergency funds, he acknowledges the need for financial preparedness.
- Living Within Means: By consistently living within your means, you can better handle unexpected expenses without resorting to debt.
- Alternative Strategies: Consider setting up a line of credit with strict access controls as a backup for true emergencies.
- Financial Discipline: Maintaining low debt levels and a healthy savings rate can provide a buffer against financial surprises.
What is the "Diderot Effect" mentioned in "The Wealthy Barber Returns"?
- Spending Begets Spending: The Diderot Effect describes how acquiring a new possession can lead to further spending to complement it.
- Awareness is Key: Recognizing this tendency can help curb unnecessary spending and maintain financial discipline.
- Impact on Lifestyle: The effect can lead to lifestyle inflation, where increased spending becomes habitual and unsustainable.
- Practical Advice: Chilton advises being mindful of this effect and making conscious decisions to avoid falling into the spending trap.
How does "The Wealthy Barber Returns" approach the topic of retirement planning?
- Start Early: The book emphasizes the power of compounding and the benefits of starting to save for retirement as early as possible.
- Consistent Contributions: Regular contributions to retirement accounts, even in small amounts, can lead to significant growth over time.
- Balance and Diversification: A balanced and diversified investment portfolio is recommended to manage risk and maximize returns.
- Plan for Longevity: Consider the possibility of living longer than expected and plan retirement savings accordingly to ensure financial security.
What role does humor play in "The Wealthy Barber Returns"?
- Engagement Tool: Humor is used to make the subject of personal finance more engaging and less intimidating for readers.
- Memorable Lessons: By incorporating humor, Chilton makes financial lessons more memorable and relatable.
- Breaking Stereotypes: The book challenges the stereotype of finance being a dry subject, making it accessible to a wider audience.
- Encouraging Action: Humor helps to lower defenses, encouraging readers to take action on the financial advice provided.
About the Author
Other books by David Chilton
Download PDF
Download EPUB
.epub digital book format is ideal for reading ebooks on phones, tablets, and e-readers.








