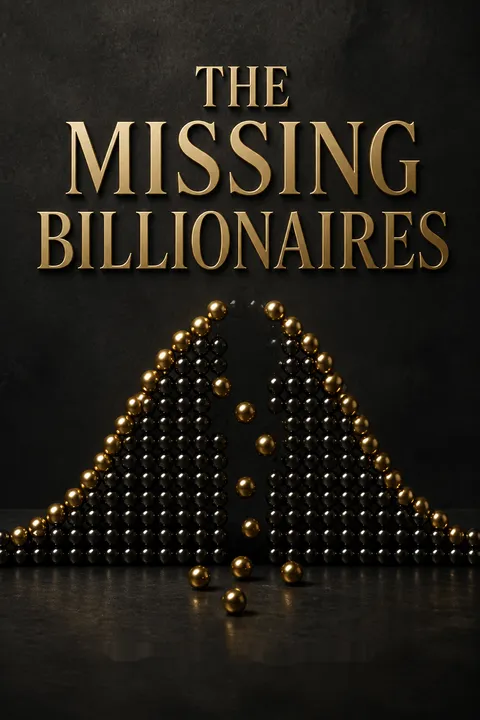


Key Takeaways
Protect the size of your bets before chasing better investments
The missing fortune. When Cornelius Vanderbilt died in 1877, his son inherited $100 million, then an extraordinary fortune. Within roughly 70 years, the family wealth had largely vanished. The authors argue that poor sizing of investment risk and spending, not a lack of good investments, helps explain why great fortunes often fail to endure. Their hypothetical calculation suggests that a diversified investment and moderate spending could have left Vanderbilt descendants enormously wealthy today, though that outcome depends on assumptions about family growth, taxes, and returns.
The question is how much. Victor Haghani’s experience at Long-Term Capital Management makes the point personal: he had about 80% of his liquid wealth in the fund, while his stake in its management company added further exposure to the same risks. Strong investments cannot rescue a portfolio that is too concentrated to survive their bad years.
The focus on position size corrects a conspicuous imbalance in financial conversation: investment stories celebrate finding winners, while survival depends on how much capital is exposed when a winner falters. This is also a lesson in organizational risk. A firm can have sound analysis and skilled people yet remain fragile if many supposedly separate assets depend on the same hidden driver. The Vanderbilt explanation is suggestive, not definitive: family preferences, inheritance patterns, taxes, and consumption also shape wealth across generations. The useful point is not that every lost fortune came from one error, but that concentration can turn ordinary volatility into an irreversible family outcome.
Scale risky positions to their edge, variance, and your tolerance
A simple game, a costly mistake. In the authors’ experiment, 61 financially trained participants could bet on a coin known to land heads 60% of the time. Given $25 and 300 flips, only 21% reached the $250 payout, while 28% went bust. A constant fraction of bankroll, around 10% to 20% in this capped game, performed far better than erratic bets or doubling down.
Size follows the odds. The Merton share is a rule of thumb for sizing a risky investment: allocate more when expected excess return is higher, and less when variance or personal risk aversion is higher. It offers a useful starting point, not a precise universal prescription. The related Kelly criterion maximizes long-run wealth growth; the authors note that its full-risk version is too aggressive for many investors.
The experiment is powerful because it strips away market jargon and shows that understanding the odds is not the same as managing them well. Its participants’ mistakes resemble familiar failures in other domains: people overreact to streaks, seek control in randomness, and change strategy after each result. The Merton share gives those impulses a stable counterweight. Its simplicity is also its limit. Real investments have uncertain probabilities, changing correlations, taxes, and outcomes that can be much worse than ordinary fluctuations. A disciplined estimate with a safety margin is more defensible than treating a neat formula as a machine for certainty.
Choose for the life your money can support, not the biggest forecast
Money is not welfare. Expected Utility is a way to compare uncertain choices by translating each possible financial outcome into its value to the decision-maker, then weighting those values by their probabilities. The idea rests on diminishing marginal utility: an extra dollar matters more when resources are scarce than when someone is already wealthy. That is why the strategy with the highest expected dollars can still be a bad choice.
Look beyond the average. In the St. Petersburg game, a fair coin produces a payout that doubles with every consecutive heads result. Its expected dollar value is infinite, yet a person with $100,000 and logarithmic utility would pay only about $18 to play. A certainty-equivalent return, or CER, expresses a risky strategy as the guaranteed return that would leave the investor equally satisfied. This broader measure also reveals why chasing one target can neglect damaging outcomes elsewhere.
Expected Utility turns a vague question, how much risk feels tolerable, into a coherent comparison across possible outcomes. Its insistence on the whole distribution is particularly valuable when a rare jackpot dominates the average, as in lotteries or speculative investments. The framework does not discover anyone’s values on their behalf: spending needs, bequests, and tolerance for loss must still be supplied or estimated. Nor does consistency guarantee that a preference is wise in every human context. Its practical strength is narrower and important: it makes trade-offs visible, so a person can see what a decision costs beyond its headline payoff.
Let equity exposure respond to the price of risk
Compare stocks with the alternative. The authors use cyclically adjusted earnings yield as one estimate of broad equities’ long-run real return, then compare it with the real yield on inflation-protected government bonds. A stock market offering a low expected return relative to safe bonds is less attractive than one offering a wider premium. This makes the proposed allocation responsive to both market valuations and the available alternative, rather than to a fixed age-based rule alone.
A promising but uncertain record. In the authors’ historical simulations, a dynamic allocation based on excess earnings yield outperformed a static stock-and-bond mix. From 1900 to 2022, one modeled strategy also beat an all-equity portfolio with lower risk. But the long history partly relies on estimated bond yields, and past returns cannot establish future gains. Earnings yield is an imperfect predictor, not a market-timing oracle.
This approach clarifies a distinction often blurred in investing advice: risk tolerance describes the investor, while the compensation for taking risk changes with market conditions. Combining a valuation measure with the real yield of a safer asset gives a decision rule tied to relative opportunity, not market mood. Yet forecasts are noisy, and a dynamic strategy can underperform for long stretches or incur tax and trading costs. The sensible interpretation is a framework for adjusting exposure within a considered range, not permission to make dramatic forecasts from one valuation statistic.
Make spending adjust to wealth, and insure against living longer
Spending and investing are linked. Expected Lifetime Utility measures the value of spending across the rest of a person’s life, including the effect of investment risk and uncertain longevity. A proportional spending rule adjusts withdrawals as portfolio wealth changes. That flexibility matters: in one example, a retiree who spent a fixed inflation-adjusted 5% of starting wealth ran out of money in 2019, despite a respectable average portfolio return. A variable plan preserved substantial wealth through 2022 by cutting spending after losses.
Longevity can be pooled. An annuity exchanges savings for income paid while the buyer lives. In the authors’ stylized example, a 65-year-old with $1 million could receive just under $50,000 annually from a fairly priced annuity. Self-managing the money meant lower expected lifetime spending because she needed reserves in case she lived longer. Fees, inflation protection, taxes, and bequest goals can change the decision.
The central insight is that a retirement plan is not simply an investment portfolio with withdrawals attached. A spending rule determines how market losses reach everyday life, while an annuity transfers one particular risk, outliving one’s savings, to a pool of people with uncertain lifespans. Those benefits may be especially important for someone who values stable consumption and has little desire to leave a large estate. The trade-off is real: annuitized wealth is less liquid and may not pass to heirs. A decision framework can clarify the exchange, but product quality and individual priorities remain decisive.
Count future earnings and real spending power as part of wealth
Your balance sheet extends beyond accounts. Human capital means the value of future earnings, usually after tax and above basic living costs. Its risk matters: a worker whose income rises and falls with the economy has stock-like human capital, while steadier employment is more bond-like. A doctor expecting $500,000 of annual income above subsistence for 30 years may have far more human capital than financial savings, but that does not make aggressive borrowing safe. Earnings estimates, career flexibility, and market correlation all matter.
Measure what wealth buys. A Constant Standard of Living annuity, or CSL annuity, is a stream of payments that maintains a person’s chosen standard of living. The book argues that broad inflation indexes may not match an individual’s needs. If personal costs rise faster than CPI, cash and Treasury bills may preserve nominal dollars while eroding future purchasing power. Inflation-protected bonds can better match long-term real spending, depending on taxes and the household’s own spending index.
Thinking in total resources corrects a common mistake among younger investors: treating a small brokerage balance as if it were the whole household balance sheet. But future labor income is not a liquid asset, and its value can fall precisely when markets fall, especially in cyclical careers. The analogy to stocks and bonds is useful as a first approximation, not a valuation that should be borrowed against mechanically. The spending-based perspective is equally valuable because financial security ultimately concerns what resources can provide. A personal inflation measure, however, should be estimated carefully rather than treated as a precise, permanent number.
Favor broad, cheap exposure over stories you cannot reliably price
Diversification is a free defense. The authors’ starting points are that large markets are fairly competitive, costs reduce investor returns, and the market portfolio is the one all investors can own at once. Index funds provide broad exposure at low cost, while concentrated stock picking adds company-specific risk that may not bring extra expected return. Their review also warns that active funds often carry higher fees, taxes, and concentration, and that investors’ actual returns can lag the funds they choose when they chase recent winners.
Demand stronger evidence for harder-to-price assets. Inflation-linked government bonds and broad equity markets have identifiable cash flows that help anchor return estimates. Private funds, individual companies, collectibles, and crypto are harder to value and may rely heavily on historical performance or uncertain resale prices. Factor strategies can have plausible explanations, but data mining, trading costs, and crowded trades can shrink apparent advantages.
The emphasis on what can be estimated is a useful antidote to persuasive investment narratives. A plausible story is not equivalent to a measurable return advantage, especially when fees, taxes, and liquidity constraints are included. Broad indexing also avoids the burden of identifying which manager or company will win in advance. Still, efficiency is a working assumption, not a law that rules out every skillful active investor or every persistent premium. The practical burden of proof should rise with complexity: an investment that cannot be priced confidently deserves a smaller allocation, not a more elaborate sales pitch.
Leverage and options can turn a correct forecast into a loss
Volatility changes the result. A leveraged exchange-traded fund resets its exposure regularly. A three-times fund therefore buys after rises and sells after falls to restore its target leverage. In a volatile market, this rebalancing creates volatility drag: the compounded result can fall far below three times the market’s return. In the book’s example, a market gain over the holding period coincided with losses in both a three-times long fund and its three-times short counterpart.
Options are tools, not magic. Options can reshape risk or help maintain a desired exposure when frequent rebalancing is impractical. But each contract has a counterparty, transaction costs matter, and protection can be expensive. The authors find that options add little value for many ordinary investors under their assumptions, while leveraged positions magnify the cost of misjudging risk. Their historical leverage example shows that 2x exposure produced a near-total drawdown, while 5x exposure was wiped out.
These examples expose a mismatch between directional intuition and compound returns. Calling the market correctly is not enough when leverage forces repeated trading or when losses leave too little capital to participate in a recovery. The same principle applies to borrowing for concentrated investments: a temporary price move can become permanent financial damage. Options can be rational when they solve a specific portfolio problem, such as limiting liability or hedging an unavoidable holding. Their complexity should be matched by a clear purpose and a full accounting of price, exposure, and worst-case loss.
Treat taxes and forecasts as uncertain risks, not spreadsheet footnotes
Tax deferral has a risk price. When an appreciated asset dominates a portfolio, selling some may improve diversification but trigger a tax bill. In one illustrative case, a portfolio with 75% in equities and large unrealized gains had a modeled optimal equity allocation of 59%, rather than simply holding everything to defer tax. Different assumptions about future tax rates, horizon, and investment returns change the answer. The point is to weigh after-tax outcomes across scenarios, not maximize wealth in one favored forecast.
Unknown probabilities still need structure. Parameter uncertainty means not knowing an investment’s true return distribution. The authors’ Ellsberg urn example shows why a known 50/50 risk can be preferable to an uncertain mix, especially across repeated decisions. Uncertainty in expected returns can reduce sensible exposure over long horizons. Since models and preferences are imperfect, use ranges, update assumptions, and avoid false precision.
Taxes are often treated as a deterministic nuisance, yet tax choices interact with concentration, future spending, and changes in law. Evaluating the full after-tax distribution is more informative than relying on a single expected return. The same discipline applies to forecasts: a probability estimate is not a fact merely because it appears in a spreadsheet. Bayesian reasoning offers a useful mental model, since prior knowledge and new evidence should jointly shape confidence. But multiplying uncertain assumptions can create an illusion of rigor. Robustness across plausible scenarios matters more than a finely tuned answer to one imagined future.
Analysis
The book’s most consequential move is to redirect attention from investment selection to decision scale. That shift makes the argument unusually cohesive: portfolio concentration, retirement withdrawals, annuities, taxes, human capital, and options all become versions of one problem, choosing exposure given uncertain consequences and personal priorities. The coin-flip experiment provides a sharp opening because it demonstrates that even transparent odds do not prevent intuitive overbetting. The family fortunes and LTCM stories then show the high stakes of that error.
Expected Utility supplies a common language for these choices, but it is a normative tool, not a neutral truth machine. Its outputs depend on estimated distributions, a calibrated utility function, and assumptions about future spending. In financial markets, those inputs are especially fragile: history is short relative to the risks that matter, market regimes change, and rare events are difficult to price. The framework is strongest when it disciplines comparisons and exposes hidden concentration, and weakest when its numerical precision disguises uncertainty in its inputs.
The book also implicitly distinguishes a good decision from a good outcome. A carefully sized investment can lose money, while a reckless bet can pay off. That distinction is central to learning under uncertainty, where vivid outcomes can distort memory and encourage imitation of luck. A practical reader should therefore treat the models as guardrails: estimate cautiously, diversify, stress-test plausible failures, and revisit assumptions as circumstances change. The authors’ preference for consistent choices is valuable, but consistency should not become rigidity. People’s needs, family structures, and capacity to bear loss evolve. The strongest application is not blind formula-following, but a repeatable process that makes trade-offs legible before events make them irreversible.
Review Summary
The Missing Billionaires receives mixed reviews, with an average rating of 3.88 out of 5. Readers appreciate the book's focus on investment sizing and risk management, praising its mathematical approach and utility framework. However, some find it overly technical and academic, lacking practical advice for everyday investors. The book's exploration of why wealthy families struggle to maintain fortunes over time is highlighted as insightful. Critics note that the content can be dense and challenging for non-finance professionals, while supporters value its unique perspective on portfolio theory and financial decision-making.
People Also Read






Glossary
Merton share
risk-based allocation ruleA rule for choosing how much wealth to invest in a risky asset relative to a safer alternative. The allocation rises with the asset’s expected excess return and falls with its variance and the investor’s degree of risk aversion. It is a useful approximation under specified assumptions, not a guarantee of optimal results in every real-world portfolio.
Expected Utility
probability-weighted welfareA method for evaluating uncertain choices by assigning a utility value to each possible outcome, weighting those values by their probabilities, and comparing the resulting averages. Utility represents the decision-maker’s welfare from an outcome, rather than its dollar amount alone. The method accounts for the fact that an extra dollar generally matters less to someone with greater wealth.
Constant relative risk-aversion (CRRA) utility
wealth-based risk preferenceA family of utility functions in which the investor’s aversion to percentage changes in wealth remains constant across wealth levels. A single parameter controls the curvature of the function: higher values imply greater risk aversion. The book uses CRRA as a practical model for comparing financial outcomes, while recognizing that actual preferences can vary with circumstances and needs.
Certainty-equivalent Return (CER)
risky return translated to certaintyThe guaranteed return that would make an investor as well off as a particular risky investment, according to that investor’s utility function. It converts a probability-weighted welfare assessment into an intuitive return measure. A risky investment can have a positive expected return but a lower, or even negative, certainty-equivalent return if its risk is too costly.
Risk-adjusted Return (RAR)
return after risk costThe book’s practical measure of an investment’s value to a particular investor after accounting for the welfare cost of risk. It is closely connected to the certainty-equivalent return and depends on both the investment’s outcomes and the investor’s preferences. It is more comprehensive than expected return alone, especially when returns are asymmetric or include severe tail outcomes.
Expected Lifetime Utility
welfare from lifetime spendingA measure of the probability-weighted utility generated by spending over a person’s remaining life, often accounting for investment returns, taxes, inflation, longevity, and bequests. It treats saving, investing, and spending as connected decisions. The objective is not simply to maximize final wealth, but to choose policies that best support valued consumption and transfers over time.
Constant Standard of Living annuity (CSL annuity)
standard-of-living income benchmarkA stream of payments designed to maintain a person’s standard of living over time, measured against a personalized spending index rather than a broad inflation measure alone. The book uses it as a benchmark for evaluating wealth and asset risk. Assets that preserve nominal value may still be risky if they fail to support this real spending stream.
volatility drag
compounding loss from fluctuationsThe reduction in compounded wealth that can result from gains and losses of similar percentage size. A 20% loss followed by a 20% gain does not restore the starting value. The effect grows with volatility and position size, and it helps explain why aggressive repeated bets and daily-reset leveraged funds can lose money despite favorable average returns.
Parameter uncertainty
uncertainty about the modelNot knowing the true probabilities and characteristics of investment outcomes, including expected returns, volatility, and correlations. It differs from ordinary risk, where the probability distribution is assumed to be known. In the book’s examples, uncertainty about expected returns can make a risky investment less attractive, particularly when exposure is held across many periods.
FAQ
What's The Missing Billionaires about?
- Focus on Financial Decisions: The Missing Billionaires by Victor Haghani explores the importance of making sound financial decisions, particularly in investment sizing and spending strategies.
- Framework for Decision-Making: The book introduces a framework based on Expected Utility theory to guide individuals through complex financial choices.
- Real-World Applications: It combines academic theory with practical insights, making it relevant for both individual investors and financial professionals.
Why should I read The Missing Billionaires?
- Timely Financial Insights: The book addresses wealth dissipation among families and offers strategies to avoid this fate, providing a fresh perspective on investment and spending.
- Comprehensive Framework: Readers gain access to a structured approach for evaluating financial decisions, leading to improved financial outcomes.
- Expertise of Authors: Victor Haghani and James White bring decades of experience in finance, lending credibility to the strategies discussed.
What are the key takeaways of The Missing Billionaires?
- Investment Sizing is Crucial: The book emphasizes that how much you invest is often more important than what you invest in.
- Expected Utility Framework: Advocates for using this framework to make rational financial decisions by weighing potential gains against risks.
- Dynamic Asset Allocation: Highlights the importance of adjusting investment strategies based on changing market conditions and personal circumstances.
What is the Expected Utility framework in The Missing Billionaires?
- Definition of Expected Utility: A method for evaluating choices under uncertainty, aiming to maximize expected satisfaction or utility from different outcomes.
- Application in Financial Decisions: Helps individuals assess trade-offs between risk and return when making investment choices.
- Real-World Examples: The book provides case studies illustrating how the framework can be applied to various financial scenarios.
How does The Missing Billionaires explain the concept of risk aversion?
- Understanding Risk Aversion: Refers to the tendency to prefer certainty over uncertainty, especially in financial decisions.
- Calibration of Risk Aversion: Suggests using a simple survey to calibrate one's level of risk aversion for consistent financial decisions.
- Impact on Financial Decisions: Higher risk aversion leads to conservative strategies, while lower risk aversion may encourage riskier investments.
What is the Merton share, and how does it relate to investment decisions in The Missing Billionaires?
- Definition of Merton Share: A formula to determine the optimal fraction of wealth to invest in a risky asset based on expected return, risk, and risk aversion.
- Application in Investing: Allows investors to make informed decisions about wealth allocation to risky investments.
- Risk-Adjusted Returns: Helps investors understand the trade-off between risk and return, ensuring adequate compensation for risks taken.
How does The Missing Billionaires address the issue of spending in retirement?
- Optimal Spending Strategies: Explores various spending policies for retirees, emphasizing alignment with investment performance.
- Merton-Samuelson Framework: Introduces a framework for lifetime consumption and portfolio choice, considering risk aversion and time preference.
- Impact of Longevity Risk: Highlights the importance of managing longevity risk to ensure retirees do not outlive their savings.
What is the annuity puzzle mentioned in The Missing Billionaires?
- Definition of Annuity Puzzle: Refers to the underutilization of annuities in retirement planning despite their benefits in providing lifetime income.
- Barriers to Adoption: Discusses reasons for low uptake, including complexity, high fees, and lack of understanding.
- Potential Benefits: Argues that annuities can enhance retirement welfare by pooling longevity risk.
What are the implications of taxes on investment decisions in The Missing Billionaires?
- Tax Considerations: Highlights the importance of understanding tax impacts on investment returns and overall wealth.
- Tax Loss Harvesting: Discusses strategies like selling losing investments to offset gains and reduce tax liability.
- Optimal Timing for Realization: Emphasizes evaluating the timing of realizing gains or losses for favorable tax outcomes.
How does The Missing Billionaires address the concept of human capital?
- Definition of Human Capital: Refers to the economic value of an individual's skills, knowledge, and experience.
- Investment in Human Capital: Encourages maximizing human capital through career choices and evaluating potential earnings.
- Integration with Financial Planning: Discusses factoring human capital into overall wealth and investment strategies.
What are the risks associated with leveraged ETFs as discussed in The Missing Billionaires?
- Volatility Drag: Explains how leveraged ETFs can suffer from volatility drag, leading to losses over time.
- Path Dependency: Highlights that performance is path-dependent, making them riskier in volatile markets.
- Potential for Total Loss: Warns of catastrophic losses during market downturns, advising caution based on risk tolerance.
What are the best quotes from The Missing Billionaires and what do they mean?
- “Any fool can make a fortune; it takes a man of brains to hold onto it.”: Emphasizes that maintaining wealth requires careful decision-making and risk management.
- “It's more difficult to hold on to wealth than it is to make it.”: Reflects challenges in preserving fortunes across generations, stressing structured financial decision-making.
- “A penny saved is two pence clear.”: Highlights the value of saving and avoiding unnecessary risks, akin to seeking high returns.
Download PDF
Download EPUB
.epub digital book format is ideal for reading ebooks on phones, tablets, and e-readers.








