

Key Takeaways
Build financial peace by managing debt and risk, not chasing a number.
Money is not the whole problem. Jared Dillian grew up with modest means, later earned millions, and argues that more money alone does not guarantee less worry. His central model reduces avoidable financial stress to two sources: debt, which creates fixed obligations, and risk, which makes financial outcomes uncertain. The aim is not to eliminate every concern or become rich at any cost. It is to arrange money so it rarely occupies the mind.
Structure beats penny-pinching. Dillian says a household can reduce pressure by making a few consequential choices well, rather than auditing every coffee or small purchase. A paid-off home and a portfolio whose swings feel bearable can matter more to peace of mind than a higher account balance paired with constant anxiety.
The useful move is shifting attention from wealth as a score to financial life as a source of cognitive load. Behavioral economics helps explain why recurring bills and volatile balances can feel disproportionately consuming: people react not just to expected outcomes, but to uncertainty, losses, and obligations they cannot easily escape. Still, debt and market risk are not literally the only sources of financial strain. Low wages, medical costs, unstable housing, and caregiving can impose pressure even on people who borrow little and invest cautiously. The model works best as a practical map of controllable financial stressors, not a complete account of hardship.
Get the house, car, and education costs right before sweating coffee.
Big choices dominate. The book challenges the familiar advice to build wealth by denying small pleasures. Dillian calculates that skipping a $3.59 coffee on 250 workdays saves about $900 a year, while a house costing $100,000 more could add roughly $110,000 in mortgage interest at the rates he discusses. An expensive car and large student loans can also create years of payments that no coffee habit can offset.
Spend attention where it counts. A smaller house, a practical car, or a less costly school may preserve room for savings and enjoyable spending elsewhere. The point is not that small purchases never matter. It is that relentless austerity can make money feel like a daily test while leaving the largest financial commitments untouched.
This is a strong application of materiality: financial attention should track the size and duration of consequences. The distinction resembles risk management in engineering, where teams focus first on failure modes with the greatest expected damage, not on every minor imperfection. The argument also recognizes that sustainable plans must leave room for ordinary pleasure. Its limit is that small recurring costs can become consequential when income is extremely constrained, and large choices are not always freely chosen. The framework is most empowering when it directs scrutiny toward decisions a household can actually influence.
Grow income and upside instead of sacrificing every small pleasure.
Expand the revenue side. Dillian describes leaving a Coast Guard career paying about $45,000 a year, completing an MBA, and joining Wall Street. Within five years, his income had risen substantially. The story illustrates his preference for increasing earning power over squeezing a few thousand dollars from an already frugal budget. He points to raises, career changes, side work, ownership, and business-building as possible routes.
Look for scalable work. A scalable business can serve many more customers without costs rising at the same rate. Dillian's newsletter business began in a frightening period with no steady revenue, earned $235,000 in its first year, and grew over time. The author stresses that the hard part is execution, not merely having an idea, and that greater earning potential requires effort and risk.
The revenue-side lens counters a common behavioral trap: expenses are immediately visible, while foregone earnings are harder to notice. Career development, bargaining, and business ownership can change the scale of a household's choices more than small cuts can. Yet the author's career leap is a vivid case, not a typical forecast. Earnings depend on health, discrimination, local labor markets, family responsibilities, and luck, and not every worker can simply trade identity for a higher-paying role. The practical lesson is to investigate earning options without treating low income as a personal failure or entrepreneurship as universally suitable.
Save early, then let accumulated wealth improve the life you actually live.
Avoid both extremes. Dillian calls the spendthrift who lives on debt a high roller, and uses the colorful label CF for someone so focused on saving that every expense becomes a battle. He argues that both can be ruled by money: one frets about preserving every dollar, the other about keeping up with payments. His preferred middle ground is to save and invest, then spend some accumulated wealth on things that genuinely add enjoyment.
Do not postpone pleasure forever. Dillian recalls earning a high salary while eating very cheap lunches and living well below his means. Buying expensive boots at age 38 marked a shift in his attitude. He frames delayed gratification as useful when it leads to future enjoyment, not when fear turns accumulation into a lifelong purpose. He also links a healthier relationship with money to greater generosity.
The chapter's most memorable correction is that frugality is not automatically virtue and consumption is not automatically vice. Research on well-being often distinguishes purchases that support relationships, meaningful experiences, or everyday comfort from status spending that quickly loses its appeal. That distinction enriches the author's invitation to spend deliberately. The suggested life-stage pattern, saving more when young and spending more later, is not a rule that fits everyone: health, dependents, retirement needs, and income uncertainty differ. The durable principle is to make saving serve a life plan rather than letting fear endlessly defer the benefits of saving.
Choose a partner who shares your money values, and keep both informed.
Money habits enter the relationship. Dillian calls choosing a spouse a major financial decision because a saver and a free spender can clash over countless purchases. He and his wife kept their accounts separate, divided shared costs according to agreed rules, and tracked each person's contribution to home equity. They have remained married for decades with few money arguments, though the arrangement is personal rather than a universal prescription.
Transparency matters more than account design. Both partners should know where the accounts are and understand household finances. Dillian warns that leaving one person financially uninformed can create dependence and make it harder to leave an unsafe relationship. For family or friends asking for a loan, he advises assuming the money is a gift unless the lender is prepared to formalize terms and accept the risk.
The strongest insight is that financial systems are also relationship systems. Separate accounts can reduce the sense that one partner must authorize the other's discretionary spending, while shared visibility protects against secrecy and financial dependence. Couples research and family-systems thinking both suggest that conflict often concerns fairness, trust, and autonomy as much as arithmetic. Still, separate accounts do not automatically prevent resentment, and joint accounts do not necessarily erase individual agency. The essential ingredients are explicit agreements, access to information, and a way to revisit the arrangement as income, caregiving, or household responsibilities change.
Keep cash liquid: an emergency reserve buys resilience and choices.
Cash has a job. Dillian recommends keeping six to twelve months of expenses readily available, using a $4,000 monthly budget as an example that calls for at least $24,000 in reserve. The money is there for events such as job loss, a broken transmission, or a pet's urgent medical care. He cautions against investing this reserve, even if inflation erodes its purchasing power, because its purpose is dependable access.
Liquidity creates options. Cash can also let someone act when a useful opportunity appears, without having to sell investments or borrow in a hurry. The author calls this the option value of cash and suggests holding about 20% of net worth in cash. That allocation is his preference, not a universal rule. He also notes that property and private-company holdings can be difficult to sell quickly.
Cash is often judged only by its return, but liquidity has insurance value: it reduces the chance that a temporary shock forces a permanent decision, such as selling a depressed asset or taking expensive debt. This is a classic trade-off between efficiency and resilience, also seen in supply chains that keep spare capacity rather than operating at maximum utilization. The right reserve depends on income stability, dependents, insurance, and access to credit. A large cash share can lose purchasing power over time, so the author's 20% figure is better understood as a personal risk preference than a general prescription.
Use credit cards as payment tools, never as unplanned loans.
Pay the statement in full. Dillian sees credit cards as useful for convenience and building credit, but dangerous as borrowing. If a discretionary purchase is not backed by money already available, he advises waiting. He recommends checking the card balance weekly so overspending can be corrected before the bill arrives. Rewards do not rescue a carried balance: a 1% or 2% benefit can be overwhelmed by interest charges near 20% in the conditions he describes.
Watch the compounding. Unlike a fixed installment loan, revolving card debt can accrue interest on an ongoing balance, making it easy for debt to grow. Dillian suggests keeping a small number of cards to reduce complexity and treating points as a minor bonus, not a reason to spend more. If full repayment is impossible, he says to examine the household budget and contact the card issuer about options.
The practical strength here is treating the credit card app as an early-warning device rather than a monthly surprise. That approach adds feedback to a payment method designed to make spending feel painless. Behavioral research on payment methods has found that less tangible forms of payment can weaken the felt cost of a purchase, which helps explain why weekly review can matter. The advice also avoids the false choice between banning cards and using them without limits. Still, a budget cannot solve a persistent income shortfall by itself. When essentials exceed income, the problem requires broader support or structural change, not just more frequent monitoring.
Treat housing as a lifestyle purchase with leveraged downside, not guaranteed wealth.
Buy below the lender's maximum. Dillian advises keeping housing costs, including mortgage, insurance, and property tax, around 25% of income. He suggests choosing a home affordable on a 15-year mortgage, even if the buyer ultimately selects a 30-year term. A house also requires maintenance, which he estimates at about 1% of its value each year on average. Its price can rise, but it can also fall.
Leverage magnifies outcomes. In his example, a $500,000 home bought with $100,000 down has $100,000 in initial equity. If the home's value falls to $400,000, that equity disappears before selling costs. A larger down payment can provide a cushion, while a smaller home can leave more money for retirement, repairs, and other goals. School districts and location may justify higher costs, but those are trade-offs to calculate openly.
A home combines shelter, consumption, and investment, which makes it unusually easy to confuse emotional value with financial return. The author's leverage example makes a central risk legible: a modest change in the asset's value can produce a much larger change in the owner's equity. Housing is not simply a bad investment, however. It can provide stability, inflation protection, and forced saving through principal repayment. The relevant decision depends on local prices, mobility, maintenance, and alternatives to ownership. A percentage rule is a useful warning light, not a substitute for a household-specific cash-flow analysis.
Buy reliable cars with terms you can escape within five years.
Do not buy the payment. Dillian recounts visiting a dealership for a Corvette and being shown a monthly payment before the salesman would explain the interest rate. The experience illustrates the information gap between a trained seller and a buyer. He recommends researching the trade-in and purchase price, examining every fee, asking directly about interest and loan length, and being willing to leave. A payment that fits this month can still conceal a costly deal.
Account for the car's full cost. Cars lose value, so a long loan can leave the owner paying for a vehicle that has depreciated or failed. Dillian recommends avoiding loans longer than five years and keeping total transportation costs, including fuel, insurance, maintenance, and depreciation, near 10% of income. He favors reliable models kept for many years, rather than repeated upgrades or leases that obscure the cost of never owning the car.
The dealership story is an example of asymmetric information: one side knows the financing structure and the other is encouraged to focus on a monthly number. Consumer protection research often identifies disclosure and comparison shopping as ways to narrow that gap. The advice to pause, ask for the rate, and walk away is therefore more valuable than any single car recommendation. Still, reliable new cars are not affordable for every household, and used cars vary in maintenance risk. The sensible comparison includes purchase price, expected repairs, insurance, and financing, rather than assuming either new or used is always the cheaper choice.
Price a degree against plausible earnings before borrowing for a lifetime.
Education is not a guaranteed investment. The book highlights $1.7 trillion in outstanding U.S. student loans at the time of writing and warns that education debt can constrain housing, family, and career choices. Some income-based repayment plans may set payments below the interest accruing, allowing the balance to grow. Student loans are also unusually difficult to discharge through bankruptcy, making the amount borrowed especially consequential.
Match cost to likely outcomes. Dillian proposes a tiered rule: he views top-tier universities as worth very high prices because of reputation and networks; suggests no more than about $40,000 of debt for a strong second-tier school; and recommends attending other schools only if they can be paid for without debt. He urges borrowers to assess the actual program, expected earnings, and repayment timeline rather than treating hope of a high-paying job as a plan.
The core financial question is not whether education has value, but who captures that value and whether it can repay the cost. Earnings premiums vary widely by institution, subject, completion, and student circumstances, so the author's tiers are provocative heuristics rather than dependable rules. Elite networks can open doors, but expensive prestige does not guarantee a particular career or salary. A sound decision compares net price after aid, realistic completion odds, likely earnings, and alternatives such as community college or vocational training. The wider policy point also matters: when easy credit meets limited price pressure, students can bear costs that institutions have little incentive to contain.
Build a diversified portfolio you can hold through market turmoil.
Design for staying power. Dillian argues that an investment strategy should account for the emotional path of returns, not just the average. A portfolio that swings sharply can prompt panic selling, interrupting long-term compounding. His proposed Awesome Portfolio divides assets equally among stocks, bonds, cash, gold, and real estate, with yearly rebalancing. A homeowner can count home equity toward real estate; investors without property can use a real-estate fund.
Treat the backtest as evidence, not a promise. Dillian reports that from 1971 the portfolio returned about 8.1% annually, with a 9.2% loss in 2008 and a 12.1% loss in 2022. He contrasts those declines with the much steeper fall in stocks during the financial crisis. The portfolio is meant to reduce volatility and make it easier to stay invested, not to guarantee gains or eliminate every bad year.
This proposal takes behavioral finance seriously: the best theoretical return is irrelevant if an investor abandons the strategy at its worst moment. Diversification across assets with different drivers can reduce volatility, while annual rebalancing imposes a simple discipline to trim winners and add to laggards. The precise equal-weight allocation remains contestable. A backtest beginning in 1971 cannot establish future performance, and housing equity is often illiquid and concentrated in one location. Gold can diversify, but it produces no income. The portfolio is best read as a coherent risk-management hypothesis whose fit depends on an investor's goals and circumstances.
Analysis
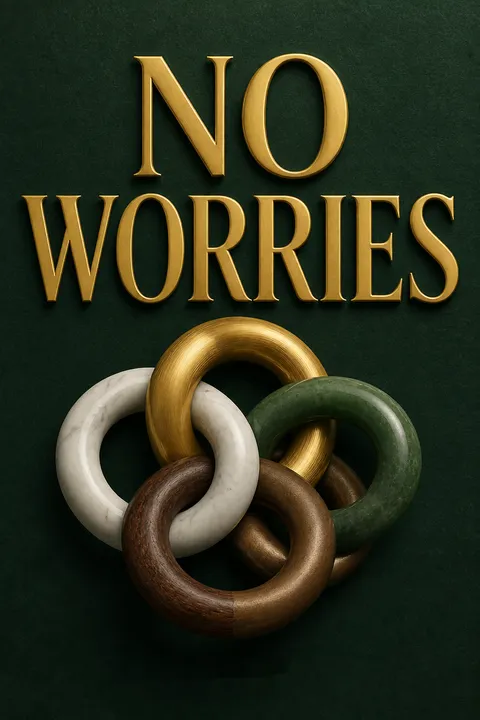
No Worries is personal finance delivered as a memoir-driven argument. Dillian uses career changes, a tense car purchase, household arrangements, and his experience in markets to support one recurring claim: financial calm depends less on maximizing wealth than on reducing the obligations and volatility that commandeer attention. Its strongest editorial choice is its ranking of decisions. The reader is invited to scrutinize housing, vehicles, and education debt, while refusing to let small purchases become a daily morality play. That reallocation of attention is both memorable and practical.
The book also resists two tidy but damaging identities: the compulsive saver and the conspicuous spender. Its middle path treats money as a tool that should enable security, enjoyment, and generosity. This is psychologically astute. Saving without permission to spend can turn prudence into fear, while spending without reserves turns optimism into fragility. The repeated emphasis on liquidity and manageable obligations gives the book a clear theory of resilience.
The limits are equally important. The claim that financial stress has only two sources is rhetorically useful but too narrow as a general explanation. Insufficient income, health shocks, unstable employment, and unequal access to housing can be causes rather than mere consequences of debt or risk. Some advice also reflects Dillian's own unusually high earnings and career options. His portfolio's historical performance is a backtest, not a forecast, and his confident prescriptions about elite colleges, cash holdings, or mortgage prepayment should not be mistaken for universal laws.
The book is most valuable as a decision framework, not a full financial plan. Its recurring test is simple: does this choice create an obligation, concentrate risk, or consume attention out of proportion to its value? That question can improve decisions without requiring readers to adopt every numerical rule. The broader promise is not a life without uncertainty, but a financial structure sturdy enough to leave attention for the parts of life that money cannot solve.
Review Summary
No Worries offers a fresh perspective on personal finance, focusing on reducing financial stress rather than penny-pinching. Readers appreciate Dillian's accessible writing style and practical advice on major financial decisions. The book emphasizes developing the right mindset, balancing spending and saving, and managing debt and risk. While some disagree with certain points, many find the overall message valuable. The "Awesome Portfolio" concept and focus on living within one's means resonated with readers. Some criticism includes inconsistencies and the author's occasional abrasiveness.
People Also Read





Glossary
Awesome Portfolio
Equal-weight diversified portfolioDillian's proposed portfolio allocates 20% each to stocks, bonds, cash, gold, and real estate. Its purpose is to diversify across financial and hard assets, reduce volatility, and make it easier for investors to remain invested through market declines. The author recommends rebalancing the allocations annually. Its historical returns are not a guarantee of future performance.
CF
Extreme saverDillian's shorthand for a person who is excessively tight with money, even when spending would be reasonable or affordable. The label describes more than careful budgeting: it points to a pattern in which small costs, tipping, gifts, and ordinary pleasures receive persistent scrutiny. The book argues that this can strain relationships and turn saving into an obsession.
High Roller
Overspender taking high risksDillian's label for someone who spends beyond a sustainable level, often relying on debt and leaving little room for savings or emergencies. High rollers may enjoy a higher standard of living in the short term, but can become vulnerable when income falls or obligations grow. The author contrasts them with extreme savers and argues that neither extreme represents a healthy relationship with money.
Revenue side
Growing household incomeThe revenue side is Dillian's way of focusing on increasing earnings rather than concentrating only on cutting expenses. It includes pursuing a raise, changing careers, adding work, building a business, or finding a role with greater earning potential. The idea is that higher income can solve financial shortfalls more effectively than years of denying modest, affordable pleasures.
Option value of cash
Cash's future flexibilityThe option value of cash is the flexibility created by holding money that is readily available. Cash can cover an emergency without selling investments, support a purchase without borrowing, or allow someone to act when an opportunity appears. Dillian sees this flexibility as valuable even when cash earns less than riskier investments, while acknowledging that inflation reduces its purchasing power.
Path dependency
Returns shaped by sequencePath dependency means that the sequence and volatility of investment returns matter, not only the average return over time. A volatile asset may have a high long-term average but still provoke an investor to sell during a decline, preventing them from receiving that average. Dillian uses the concept to argue that an investment strategy must be emotionally sustainable as well as financially plausible.
Loan-to-value
Mortgage relative to home valueLoan-to-value, or LTV, is the mortgage balance divided by the value of the property. A lower LTV means the borrower has more equity in the home and a larger cushion against a fall in prices. Dillian describes LTV as an important predictor of mortgage default risk and encourages buyers to make a substantial down payment when they can.
Cash-secured
Purchase backed by available cashA purchase is cash-secured when the buyer already has enough money available to pay the credit-card charge in full. Dillian uses the idea to distinguish credit cards used for convenience from credit cards used to borrow for discretionary spending. The card payment may arrive later, but the funds to cover it are already set aside.
Download PDF
Download EPUB
.epub digital book format is ideal for reading ebooks on phones, tablets, and e-readers.








