

Key Takeaways
Restore middle-class purchasing power, not merely consumer restraint
The problem is unequal means. Robert Reich argues that the Great Recession was not simply caused by Americans spending too much. As the economy expanded, wages for most workers failed to keep pace, while a growing share of income went to the richest households. The result was a middle class unable to buy as much as the economy could produce without borrowing heavily. In 2007, the richest 1 percent received 23.5 percent of national income, near the 1928 peak. A recovery that repairs banks but leaves this imbalance intact, Reich warns, will struggle to sustain jobs and growth.
Demand needs broad incomes. Reich’s central proposal is to make economic gains more widely shared, so households can spend, save, and withstand setbacks without relying on ever-rising debt.
The argument connects distribution to macroeconomic stability: households that spend most of each additional dollar can support demand more directly than households that save a large share. That makes wage growth and inequality relevant to the health of businesses, not only to fairness. The mechanism is persuasive, but it is not a complete account of recessions. Credit conditions, productivity shocks, monetary policy, and global imbalances also matter. Reich’s strongest claim is narrower: when workers’ purchasing power persistently trails production, debt can postpone the mismatch, but cannot resolve it.
When income piles up top, debt can hide a demand shortage
Marriner Eccles saw the pattern. Eccles, a Utah banker who became chair of the Federal Reserve in 1934, initially tried to protect his banks by calling in loans. He realized that this individually sensible response was worsening collective hardship: businesses lost credit, activity fell, and more people lost work. He came to see concentrated income as a deeper cause of the Depression. Wealthy households could not spend all they earned, while ordinary households lacked the purchasing power to buy the economy’s output.
Borrowing delayed the reckoning. In Eccles’s account, families used credit to keep buying while income flowed upward. When lenders and borrowers reached their limits, spending fell, businesses cut jobs, and declining incomes further weakened demand. Reich compares that mechanism with the years before 2008, when rising household debt and asset bubbles masked weak wage growth. Inequality does not mechanically cause every crash, but it can make an economy dependent on fragile borrowing.
Eccles’s experience makes a valuable distinction between private prudence and public consequence. A bank can reduce its own risk by restricting loans, yet the resulting contraction can damage customers and the wider economy. This resembles the fallacy of composition: what is sensible for one actor may be harmful when everyone does it at once. The account also resists treating debt as the whole diagnosis. Still, income concentration alone cannot explain why a particular bubble forms or bursts. It helps explain why the economy can become vulnerable to credit-driven growth.
Pay workers enough to become customers for what they produce
Ford linked wages and sales. In 1914, Henry Ford raised pay for workers on his Model T production line to $5 for an eight-hour day, roughly three times the typical factory wage. The higher pay drew criticism, but it also helped workers afford the cars they made. Ford’s choice illustrates the book’s basic bargain: workers are also consumers, and their earnings return to businesses as demand for goods and services.
Productivity needs buyers. A modern economy can make more than its population can afford. If workers’ pay lags behind output, companies may have less reason to invest in additional capacity, even when production technology is improving. Reich uses Ford to show why wages are not only a cost to businesses. Across an economy, they are also a source of customers. The bargain breaks when the rewards of growth stop reaching enough households to sustain demand.
Ford’s example neatly joins labor economics to business strategy. Higher wages can raise costs for an individual firm, but they can also strengthen demand across the market, particularly when many firms follow suit. The case is memorable because it shows workers in two roles, as producers and as customers. It should not be mistaken for proof that every wage increase pays for itself through sales. The effect depends on competition, productivity, prices, and where workers spend. Its larger lesson is that a firm’s cost accounting and an economy’s demand accounting are not the same thing.
A rescued financial system can coexist with a broken real economy
Wall Street is not Main Street. During the 2008 crisis, policymakers moved quickly to stabilize major banks and financial markets. Reich accepts that emergency action helped prevent a deeper collapse, but argues that restoring financial firms did not automatically restore household incomes, jobs, or small-business credit. The financial economy provides useful services, including lending and payments, but it is not identical to the real economy where people work and businesses produce goods and services.
A bailout can miss its purpose. Reich criticizes the tendency to treat financial stability as if it guarantees broad prosperity. He describes a system in which banks recovered and executives again received large rewards while many families faced unemployment and foreclosure. His point is not that finance is unnecessary. It is that policy should ask whether financial institutions are supporting productive activity and ordinary livelihoods, rather than treating their survival as the final measure of recovery.
This distinction remains useful in any crisis: aggregate market indicators can improve while households experience insecurity. It also highlights a governance problem. Financial institutions can be systemically important, giving policymakers reasons to prevent panic, while the costs of rescue may fall unevenly. The challenge is to preserve essential payment and credit functions without protecting executives or investors from every consequence of risk. Reich’s criticism can sound dismissive of finance, but the more defensible reading is that financial stability is necessary, not sufficient, for a healthy economy.
Shared postwar prosperity came from policy, bargaining, and public investment
The Great Prosperity was built. Reich calls 1947 to 1975 the Great Prosperity. During these decades, labor productivity and median family income roughly doubled, and the gains were spread more broadly than in the decades before or after. The period was supported by policies and institutions: unions and minimum wages strengthened worker bargaining power; Social Security and unemployment insurance protected income; public universities, highways, and research expanded opportunity and productive capacity.
Growth and sharing reinforced each other. The highest federal marginal income tax rate reached 91 percent under President Eisenhower, yet the economy grew strongly. Reich uses this record to challenge the claim that broad prosperity requires very low taxes on top earners. The era was far from equal: racial discrimination remained pervasive, women faced barriers, and many workers were excluded from protections. Still, its experience suggests that sharing growth and expanding public capacity can coexist with economic dynamism.
The postwar example reframes prosperity as an institutional achievement, rather than a reward delivered automatically by markets. Investments in education, infrastructure, and research can raise the productive capacity that later supports private activity. Labor bargaining can also help workers share productivity gains. The period is a useful counterexample to the idea that inequality is always necessary for growth, but it is not a clean experiment. Wartime production, global circumstances, and demographic change also shaped outcomes. A fair reading treats the era as evidence that inclusive growth is possible, not as a blueprint that can be copied unchanged.
Three coping strategies concealed stagnant wages until families hit limits
Households patched the gap. Reich identifies three coping mechanisms that let families maintain spending while pay stagnated: more women entered paid work, workers put in longer hours, and households saved less while borrowing more. By the mid-2000s, the typical American worker put in more than 2,200 hours a year, around 350 hours more than the average European worker. Household debt reached 138 percent of household income by 2007, while the personal saving rate fell to about 3 percent.
Each workaround had a ceiling. More paid work left less time for care and rest. Longer hours could not expand the day. Debt and home equity borrowing depended on lenders and housing prices continuing to cooperate. When the housing bubble burst, families could no longer use credit to sustain spending. Reich’s diagnosis shifts attention from blaming borrowers alone to the stalled incomes that made borrowing seem like a substitute for wage growth.
The three-part account is compelling because it treats household behavior as adaptation to constraints, not simply as individual irresponsibility. It also helps explain why apparently robust consumption can coexist with declining security. The time-use dimension matters: unpaid care and exhaustion do not show up cleanly in measures of output. At the same time, households made varied choices, and stagnant wages were not the only reason for borrowing. Housing speculation, credit incentives, and policy also shaped the boom. The framework works best as a map of pressures, not as a claim that every family followed the same path.
China cannot replace U.S. demand while its households receive less
A growing economy is not always a growing market. Reich challenges the hope that Chinese consumers could simply replace American consumers after the crisis. In 2009, personal consumption accounted for about 35 percent of China’s economy, down from nearly 50 percent a decade earlier, while investment rose to 44 percent. A large share of growth went to companies and production rather than household incomes and spending.
The imbalance differed by country. Reich describes the United States as producing too little purchasing power for its middle class, and China as directing too much income toward investment and production. Chinese families also had strong reasons to save, including limited social protections for health care, education, and retirement. The lesson is that global trade cannot permanently solve a domestic distribution problem. Selling more abroad may shift demand between countries, but it cannot substitute for durable purchasing power at home.
This section broadens the argument beyond U.S. domestic policy. Trade imbalances are not just about exchange rates or national thrift; they reflect how income is distributed within economies and what governments encourage firms and households to do. The comparison also cautions against assuming that a large population automatically creates an enormous consumer market. Yet national consumption shares can change with development, demographics, and policy, so the 2009 figures describe a moment, not an immutable Chinese model. Reich’s point is strongest as a warning against treating exports as a simple replacement for household income.
Relative losses become political anger when the rules look rigged
A fall feels worse beside a rise. Reich draws on research about loss aversion, the tendency for losses to hurt more than comparable gains please. In one experiment, people who received a mug demanded roughly twice as much to give it up as other people were willing to pay for it. He argues that a declining standard of living is especially painful when people remember what they once had and see the wealthy continuing to prosper.
Perceived unfairness changes the response. Reich’s classroom exercise asks one student to divide a pretend $1,000 with a partner, who can reject an unfair offer so neither receives anything. Many reject small shares rather than let the other person keep most of the money. He uses the exercise to explain why bailouts, executive bonuses, and unequal sacrifices can fuel anger. His fictional 2020 Independence Party victory dramatizes the danger of that anger turning into nationalism and scapegoating.
The section adds an important psychological and political layer to material hardship. People judge outcomes not only by absolute income, but by fairness, status, and whether others appear to follow the same rules. That helps explain why a small, highly visible privilege can provoke more anger than a larger but less legible inequality. The classroom game captures one mechanism, though real voters weigh many competing interests and do not respond as a single bloc. The fictional election is best read as a warning scenario, not a prediction: resentment can be politically mobilized, but its direction is not predetermined.
Use wage supports and public investment to rebuild the bargain
Reich proposes a policy package. His plan includes a reverse income tax that adds money to workers’ paychecks, funded partly by a carbon tax and higher taxes on top incomes. For example, he proposes a wage supplement of up to $15,000 for full-time workers earning $20,000 or less. He also calls for wage insurance and training when workers lose jobs, stronger early education, more accessible college financing, Medicare coverage for all, and better public transportation and other shared services.
Reform includes political rules. Reich argues that campaign finance and lobbying must change so concentrated wealth cannot dominate policymaking. He proposes public election funding and anonymous political contributions. These measures aim to strengthen incomes, opportunity, and public goods while reducing the influence of money in politics. The package is ambitious, and its individual parts would require scrutiny, but its organizing idea is clear: economic security and broad purchasing power are conditions for durable growth, not afterthoughts.
The proposals translate the book’s diagnosis into a coherent goal: increase household resources, improve access to education and health care, and reduce the political leverage of concentrated wealth. Linking carbon pricing to wage support is especially notable because it pairs an environmental incentive with help for households bearing higher energy costs. The plan also raises difficult design questions. Wage subsidies must avoid encouraging employers to hold wages down; education vouchers depend on school quality and accountability; and tax estimates depend on behavioral responses. Those complications do not erase the case for reform, but they make implementation and evaluation as important as the headline principles.
Analysis
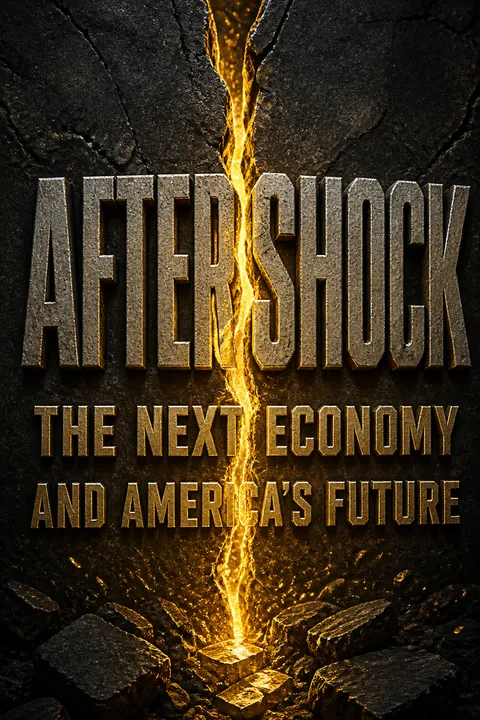
Aftershock is a political economy argument organized around a memorable causal chain: income concentrates, household purchasing power weakens, borrowing fills the gap, and credit-dependent growth becomes vulnerable to collapse. Reich’s strongest move is to connect macroeconomic demand with lived experience. The worker is not merely a production cost; the worker is also a customer, a parent, a borrower, and a citizen deciding whether institutions are legitimate. That wider frame explains why an economic downturn can become a crisis of trust. The historical structure gives the book force. Marriner Eccles’s account of the Depression, Henry Ford’s wage decision, and the postwar expansion each make abstract claims tangible. The comparison between 1928 and 2007, when the richest 1 percent received more than 23 percent of income, supplies a sharp recurring image. The postwar decades challenge the assumption that high inequality is the price of growth, while the three coping mechanisms show how families absorbed pressure before it appeared in conventional measures of prosperity.
The analysis is strongest when it treats inequality as a vulnerability that amplifies instability, rather than as a single trigger for crisis. Financial deregulation, credit practices, monetary policy, technological change, and international flows also shape downturns. The historical evidence supports Reich’s concern but does not isolate one cause. His policy proposals likewise vary in evidential strength and would require careful design, especially where taxes, vouchers, and labor incentives interact.
The book’s 2010 setting matters. Its imagined 2020 populist victory is a scenario designed to clarify political risks, not a reliable forecast. Its lasting insight is less predictive: economic pain becomes especially dangerous when people believe sacrifices are uneven and the rules are written for insiders. Broad-based prosperity, then, is both a demand-management strategy and a source of democratic legitimacy. The argument asks readers to assess recovery not only by financial markets or national output, but by whether ordinary households can share in growth without borrowing against their future.
Review Summary
People Also Read

Glossary
Basic bargain
Shared wages and demandReich’s term for the relationship between workers’ earnings and the economy’s capacity to produce. Workers are also consumers, so their wages help create demand for goods and services. When pay fails to share in productivity and economic growth, households may borrow to maintain spending, while businesses face weaker demand for what they can produce.
Great Prosperity
Broad postwar U.S. growthReich’s name for the period from about 1947 to 1975, when productivity and typical family incomes rose substantially and economic gains were more widely shared. He links the period to near-full employment, labor unions, social insurance, public investment, and wider access to education. The term describes an era of broad prosperity, not a claim that the period was equal or free of exclusion.
Coping mechanisms
Work and debt workaroundsReich’s label for three ways American households maintained consumption while many wages stagnated: more women entered paid employment, workers put in longer hours, and families reduced savings or borrowed more. These measures helped conceal weakening purchasing power for a time, but each had limits. In particular, rising debt and home equity borrowing could not continue indefinitely.
DINS
Double income, no sexAn acronym Reich uses humorously for households in which both adults work so many hours that time for intimacy and shared life is squeezed. It illustrates the human cost of relying on additional paid work to compensate for stagnant wages. The term is a shorthand within his discussion of families reaching the limits of longer working hours.
Reverse income tax
Government wage supplementA policy that adds money to eligible workers’ pay rather than collecting income tax from them. Reich proposes extending wage supplements beyond the lowest-income workers, with the payment declining as earnings rise. He argues that this would raise the purchasing power of households likely to spend much of the added income, supporting both living standards and economic demand.
Reemployment system
Support for finding new workReich’s proposed replacement for an unemployment system designed mainly to tide workers over until old jobs return. It would help people move into new work through wage insurance when a new job pays less, income support during approved training, and additional education for fields with labor shortages. A proposed employer severance tax would help cover the social costs of layoffs.
About the Author
Other books by Robert B. Reich
Download PDF
Download EPUB
.epub digital book format is ideal for reading ebooks on phones, tablets, and e-readers.








